2026-08-28
No body content available.
via InvestAnswers
No body content available.
No body content available.
No body content available.
No body content available.
No body content available.
No body content available.
The Signal
Like many people drawn to the stock market, one of the first books I read was
Reminiscences of a Stock Operator
. It follows Jesse Livermore’s rise, crashes, and recovery, with a central lesson: success in markets requires patience, emotional discipline, and listening to the tape rather than fighting it. As someone who spends much of his life thinking several years into the future, that lesson has kept me honest. It forces me to think in bets rather than certainty and look for a signal.
Standard deviations or sigmas became a central part of my signal framework when I began as an options trader. I came to view them as a baseline for identifying moves large enough to suggest a potential change in trend, whether through capitulation or breakout. Combining that search for multi-sigma moves with Livermore’s respect for the tape and my preference of studying Elliott Wave patterns, I looked for moments when the larger pattern appeared to be approaching an inflection point and then waited for the market itself to tell me when conviction should become position size.
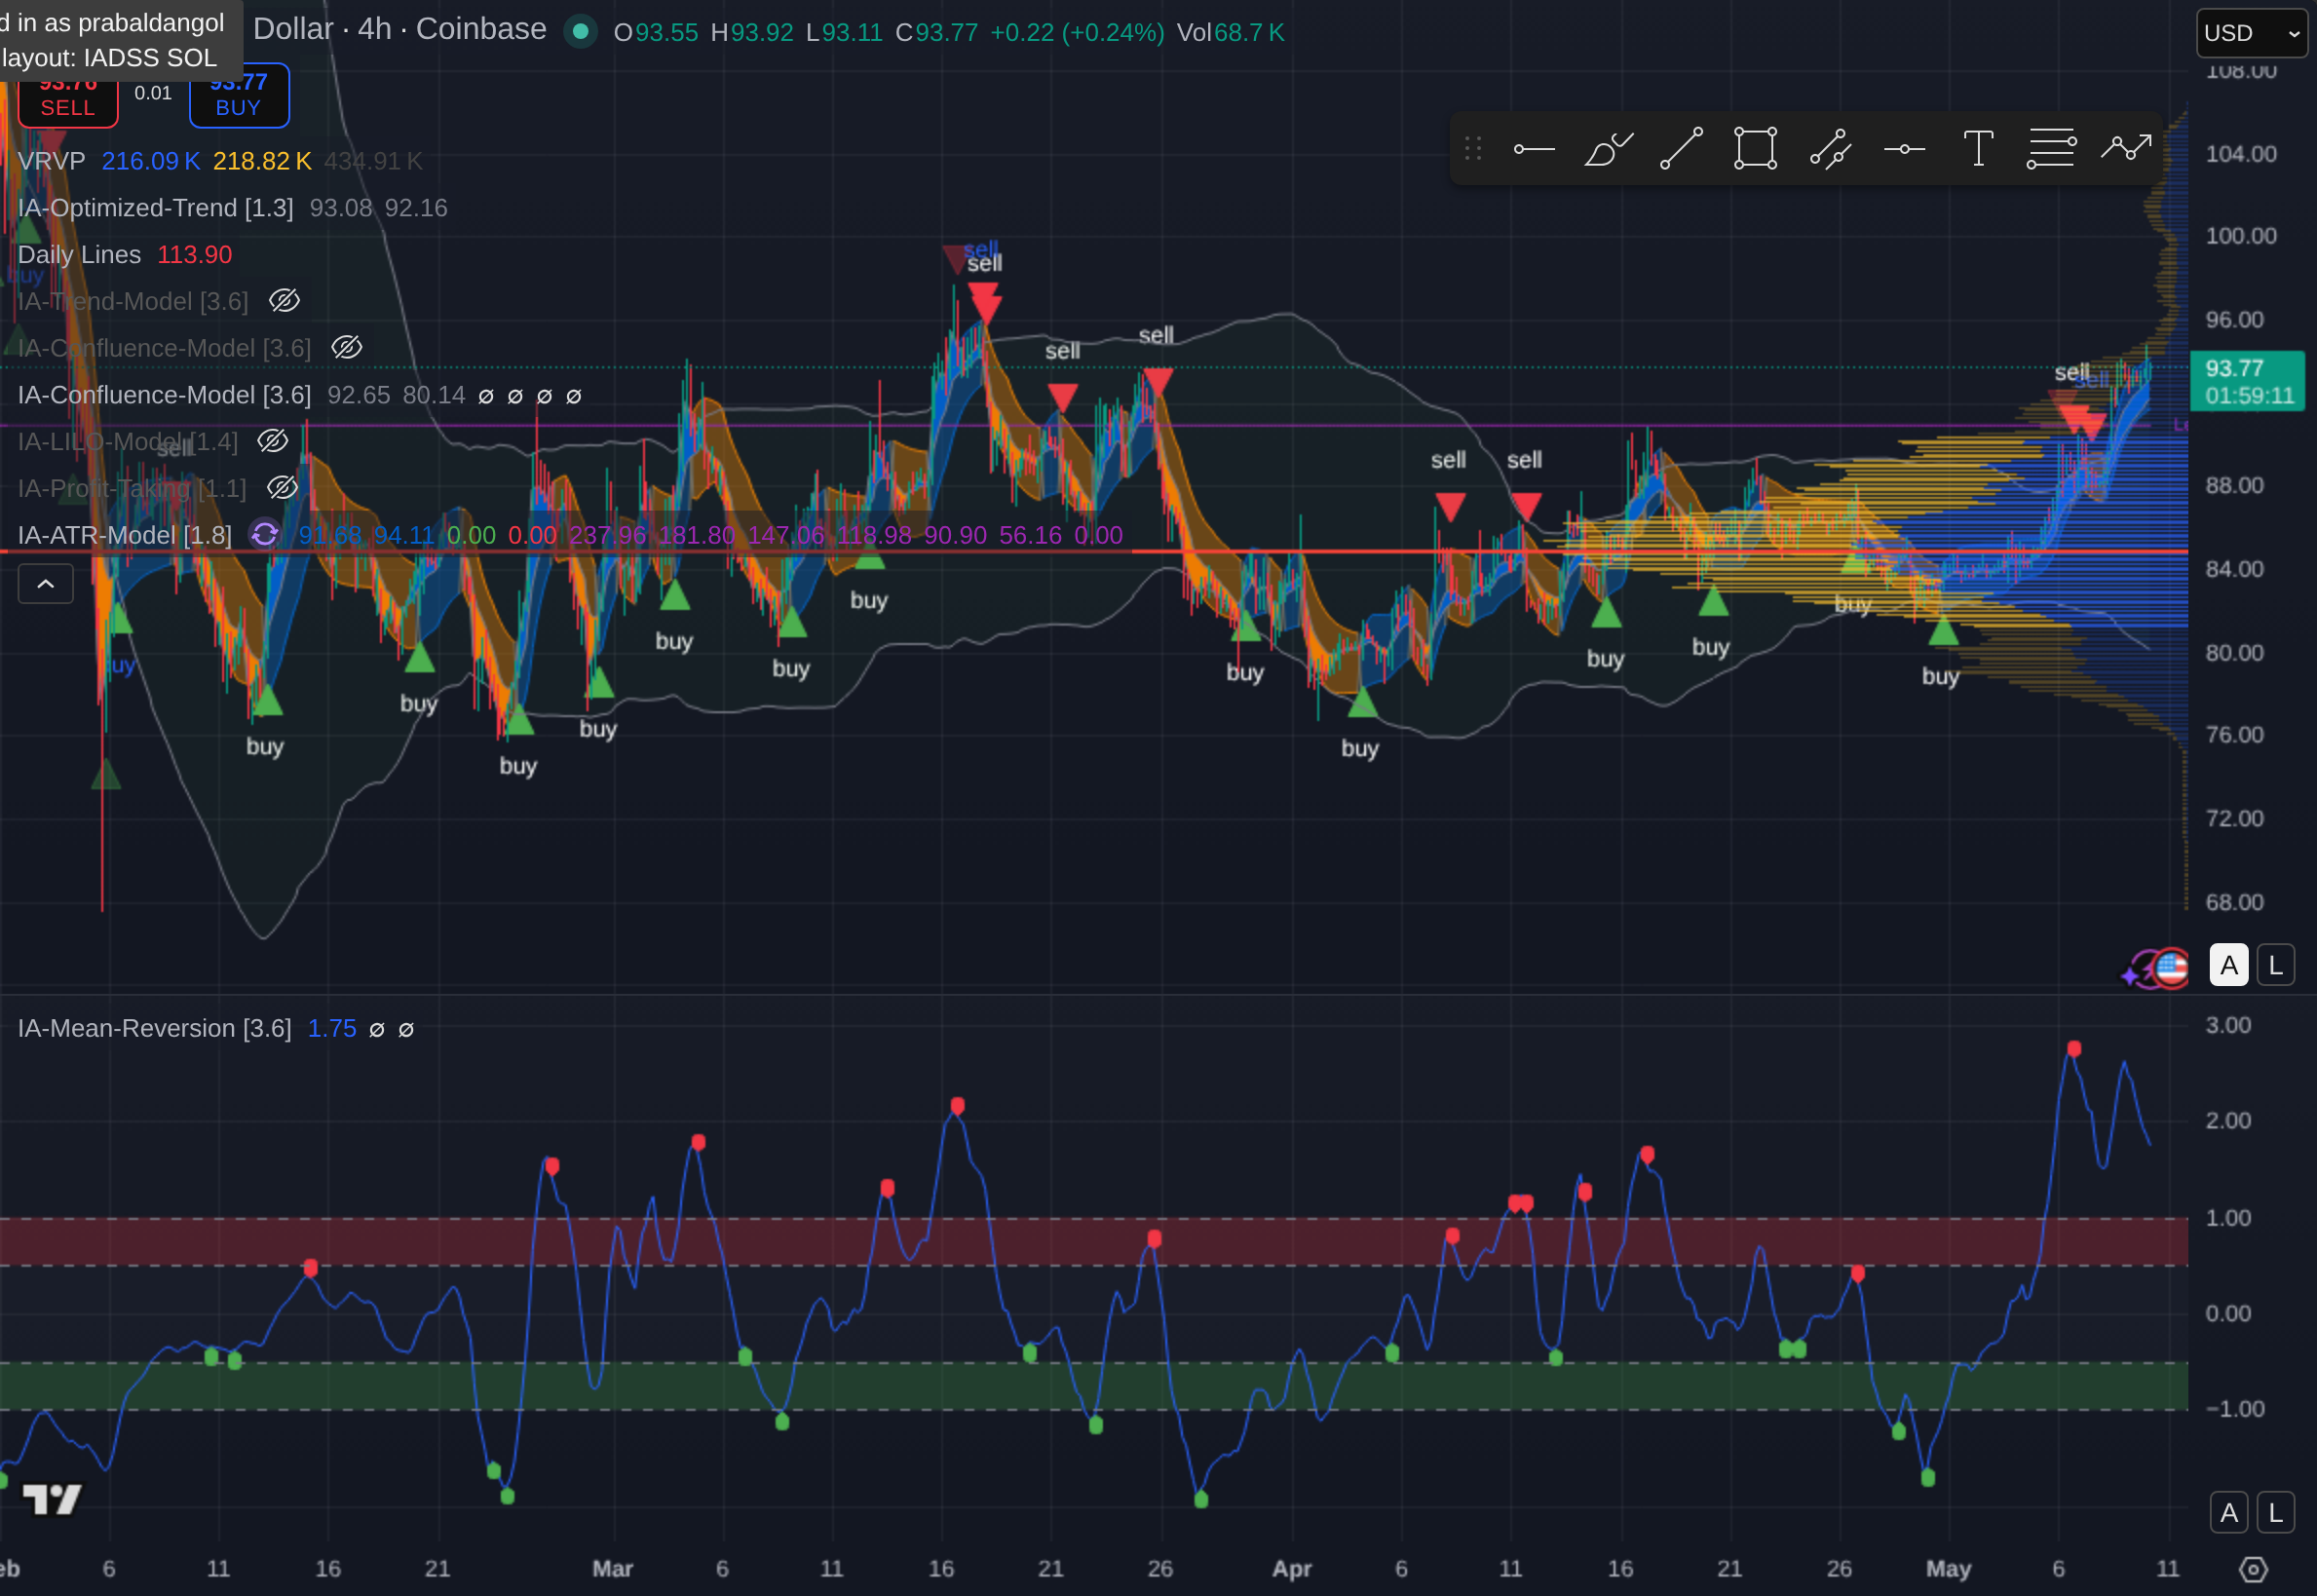
Bitcoin just delivered the kind of week that should make an investor stop and ask a different question. It rose roughly 22% against a one-sigma weekly move near 3%, about a seven-sigma move and broke above its 200-day moving average in the same week. That combination has appeared only twice in the last decade. Both prior episodes led to substantial further gains.
The pattern is evidence, never a mechanical price target. It signals that the tape is updating the story. The useful question is why this event is appearing now, after two years in which Bitcoin’s price has done little while almost everything around it changed.
Most people have focused on Bitcoin’s bear market since October. I have been more focused on those last two years. The first quarter of 2024 brought the launch of the spot Bitcoin ETFs, followed by the election of a U.S. president who embraced crypto. If Bitcoin ever had a classic “buy the rumor, sell the news” moment, 2024 was it.
Then came the inauguration and the meme-coin launch, making clear that many decentralization ideologues would be uncomfortable with the direction of travel. At the same time, AI offered the seduction of parabolic returns that had long drawn capital into crypto. The result was a two-year consolidation: early believers and ideologues had reasons to sell, while ETFs, new products, and political acceptance steadily expanded the potential buyer base.
This two-year period is what I have called Bitcoin’s silent IPO. Bitcoin never filed an S-1. It had no management team, underwriters, roadshow, earnings estimates, or conventional valuation model. Yet it has undergone the economic equivalent of an IPO: a long transfer of ownership from early believers and concentrated holders in the private market toward a broader, more institutional, regulated buyer base.
The last two years were not empty time. They were time for distribution, absorption, and acceptance. ETFs made ownership easier. Custody became more institutional. Political acceptance broadened. Products and infrastructure gave conventional pools of capital a way to own Bitcoin without first becoming crypto natives. At the same time, some of the people who got there earliest did what rational owners of a wildly appreciated asset do: they rebalanced, monetized, or turned toward the next frontier, especially AI. That selling did not necessarily express lost conviction. Often, it reflected a change in portfolio arithmetic. When a small allocation becomes a dominant share of wealth, reducing it is risk management.
This is what an IPO does. It distributes an innovation. It changes who owns the asset, who can own it, and what kind of capital sets the marginal price. The process can be volatile and emotionally unsatisfying because the owners who saw the earliest promise are not always the owners who finance the next phase. But the change in ownership can be the condition that makes the next phase possible.
Bitcoin’s current move therefore matters in context. It arrives after the distribution. It arrives after institutional pathways have been built. And it arrives as the world is discovering that Bitcoin was never only the story. Bitcoin was the gateway to a much larger financial architecture, one that may become increasingly necessary as AI changes the speed of economic life.
The Crypto Gateway
Bitcoin’s history reaches beyond Bitcoin itself. It established that scarce digital value could be created, owned, and transferred over the internet without requiring a central intermediary to validate every exchange.
The Bitcoin white paper solved the double-spending problem in a practical way. In the physical world, a dollar bill cannot be handed to two people at once. In the digital world, copying information is trivial; preventing the same digital unit from being spent twice had required a trusted intermediary. Bitcoin offered another method: a distributed network that could agree on ownership and transaction history without relying on a bank, broker, or state database as the sole recordkeeper.
That breakthrough opened a gateway. It made digital bearer assets imaginable. It made the transfer of unique digital property possible. It created a new way to think about trust, ownership, settlement, and collateral on the internet.
Marc Andreessen saw this clearly in his 2014 essay,
Why Bitcoin Matters
. He described the applications that could follow from a new form of digital property: digital contracts, keys, ownership of physical assets, stocks and bonds represented digitally, global payments, micropayments, and money that could move with far less friction. Bitcoin introduced a new financial and computational primitive.
It took time for that primitive to become an ecosystem. New technologies do not generally eliminate the old system and then begin immediately from a clean slate. They enter the old system, expose its limitations, and slowly merge with it. Personal computers did not instantly replace mainframes. The internet did not instantly replace retail, media, or finance. Cloud computing did not instantly replace enterprise servers or software. The old and the new coexist until the new architecture becomes useful enough, trusted enough, and simple enough to alter the behavior of everyone around it.
Bitcoin has increasingly become the monetary foundation of this ecosystem: a scarce, global, digitally native store of value that can function as collateral across time. The broader crypto ecosystem has pursued the applications implicit in the original breakthrough. Stablecoins make dollars programmable and continuously transferable. Tokenization makes ownership and collateral machine-readable. Smart contracts make rules executable. Wallets create native accounts for people and eventually for software agents. On-chain systems make settlement, auditability, and permissions capable of becoming software rather than a sequence of emails and reconciliations.
Not every application will work. Not every token will matter. The point is larger: Bitcoin opened the door to a financial architecture built for the internet. The next question is what happens when the internet is no longer populated primarily by people clicking buttons, but by agents that can research, negotiate, execute, pay, and reallocate continuously.
Human Time Was the Old Operating System
Artificial intelligence is the first technology that manufactures more time on one side of the ledger while extending it on the other. It manufactures time because digital agents can perform an expanding share of economically useful work without sleeping, commuting, losing focus, or waiting for Monday. It extends human time because the same accelerating tools are being directed toward biology, diagnostics, drug discovery, and diseases of aging as we saw with Moderna’s cancer vaccine this month.
We are still arguing in the wrong units. Whether models truly reason, whether every benchmark is meaningful, and whether artificial general intelligence arrives in one year or ten are consequential questions. But the operative fact is already visible: capability is advancing faster than the institutions built to absorb it.
AI disrupts through time. It changes the speed at which work, competition, and adaptation occur.
Every structure through which we organize economic life is a synchronization protocol for human bodies: the quarter, the fiscal year, the annual budget, the four-year political cycle, the four-year degree, the thirty-year mortgage, the forty-year career, and the discounted cash-flow model with a terminal value attached to its end. None was derived from an eternal principle. Each was calibrated, explicitly or implicitly, to how long it takes a person to learn, concentrate, coordinate, decide, execute, recover, and age.
For most of history, human time was the hidden governor of output. A firm moved only as fast as its people could research, communicate, write code, reach consensus, and deliver. Even exceptional organizations were constrained by meetings, distance, fatigue, hiring, managerial span, and the basic difficulty of getting people to act together. Quarterly reporting existed because closing the books took time. Annual budgets existed because allocating resources demanded deliberation. Markets closed because the people running them needed rest.
Human time was the operating system of industrial capitalism.
The useful measure of AI is the amount of skilled human work time a system can reliably compress. We are already moving toward that language: asking how long a task would take a capable human and whether a model can complete it with sufficient reliability. Human time has become the denominator of the machine world.
The slope will be debated, and it should be. Reliability matters more than isolated demonstrations. But the direction is clear. Systems are moving from answering questions, to completing bounded tasks, to running longer chains of research, code, testing, analysis, and execution. The question is not whether every job disappears tomorrow. It is what happens when the share of valuable work that can be delegated compounds year after year.
The emerging production function is therefore changing. It is no longer only labor and capital. It is capital, energy, compute, tokens, and human judgment. Tokens are becoming units of machine cognition and machine labor. They are not merely a technical metric. They represent an increasing share of work that used to be supplied through human hours.
Organization Versus Fleet
A well-run knowledge worker may deliver roughly 2,000 paid hours a year, and materially fewer once meetings, context switching, coordination, and recovery are removed. A digital agent has 8,760 hours of calendar availability. Parallelism supplies the larger multiplier.
You do not hire an agent in the historical sense. You release ten, one hundred, or one thousand. If you still can’t imagine this, sign up for Grok Bot for one month and see. They can test competing hypotheses, write alternative implementations, monitor operations, reconcile accounts, review documents, search for anomalies, and begin again continuously. The binding constraint begins to shift away from recruiting, office space, and managerial span. It becomes compute, data, energy, capital, and the quality of the person or system directing the fleet.
The relevant comparison is no longer person versus model. It is organization versus fleet.
A company operating a capable fleet against a company operating through conventional staffing is not simply twenty percent more efficient. The two are on different clocks. One remains bound by biological coordination. The other has begun to compound machine execution. The divergence is geometric rather than linear.
The human premium migrates upward: to judgment, problem formulation, taste, trust, accountability, and capital allocation. Machines compress the distance between a decision and its execution. People determine the objectives, limits, responsibilities, and values behind the work.
But that distinction should not minimize the economic change. A competitor can now build, test, distribute, and improve a product inside a period that formerly would have been spent scheduling the kickoff meeting. Research itself develops a latency problem. An analyst may spend six weeks understanding an industry only to find that a new model release, pricing change, or agentic workflow has altered the competitive landscape before the work is published. Diligence becomes stale inside its own window.
That is why AI is ultimately a time problem for investors. It can improve earnings, raise productivity, and create entirely new markets. It can also reduce the trusted duration of an advantage. This is why Charlie Munger famously said “technology is a killer as well as an opportunity.” A company may be excellent today and still be difficult to underwrite three years from now if the half-life of its moat is declining faster than the discount rate can compensate.
Compression Meets Atoms
The compression arrives in sequence, and the sequence matters because each step moves closer to the physical world. This is why my first focus from an investment perspective for AI has been the infrastructure to build tokens and feed the agents.
Agentic coding comes first because software is the most malleable part of the economy. An agent can read documentation, write code, run tests, find failures, fix them, deploy, and begin again without waiting for the next business day. That is not merely a software-industry story. Software is embedded in finance, logistics, manufacturing, medicine, media, retail, defense, and energy. If the time to build and improve software collapses, so does the time required to redesign every industry software touches.
Consumer and enterprise agents follow, compressing transaction time: research synthesis, procurement, customer service, contract review, compliance monitoring, reporting, and administration. Then AI moves toward the physical world through world models, autonomous vehicles, industrial automation, robotics, and humanoids. A fleet can collect data overnight, simulate edge cases in parallel, and distribute improved capability to every deployed unit. One machine’s lesson can become every machine’s lesson.
Atoms keep their own clock. Compute cannot repeal it.
Concrete cures on its schedule. Turbines, transformers, transmission lines, fabs, cooling equipment, and data centers involve multi-year lead times. Permits, interconnection queues, construction, and public consent often take longer. Biology still requires validation. Trust, due process, and legitimacy cannot be generated by inference.
This unevenness is the thesis. As cognition becomes more abundant, the bottleneck migrates: from cognition to compute, from compute to energy, from energy to physical throughput, and finally to institutions. The last layer may be the slowest because it is made of consent and slowed by the bureaucracy of enterprises.
The gap between digital capability compounding in months and physical capacity moving in years is where much of the next cycle’s dislocation will live. It is also where the opportunity lives: energy, grid infrastructure, advanced compute, networking, data centers, specialized materials, and scarce collateral matter because they do not compress at the speed of software.
GDP Was Built for Human Time
Productivity is a time equation. GDP was designed for an economy dominated by physical output and human labor delivered in defined periods. It records factories, construction, wages, and market transactions extremely well. It sees less of the value created when intelligence is delivered at near-zero marginal cost, software improves continuously, and an agent compresses a week of professional work into an hour.
The result is a measurement gap. The national accounts sample a compounding digital economy through quarterly and annual schedules. Finance settles continuous commerce in batch windows. Markets process continuous change around quarterly disclosure. GDP remains useful; its view is increasingly late and incomplete. Policymakers can read muted productivity, soft employment, or backward-looking inflation while digital output accelerates underneath the surface.
Financial Time Has to Catch Up
AI can compress the time required to create value. Economic time will not follow unless the financial system can move value at a comparable speed.
Finance still runs through batch processes, settlement windows, banking hours, fragmented payment rails, manual compliance, and backward-looking risk review. Those structures were rational when information and commerce moved at human speed. They become a hard constraint when agents can negotiate contracts, manage inventory, extend credit within limits, rebalance portfolios, and pay suppliers continuously.
The rails of an AI economy need to be continuous: real-time settlement, programmable payments, tokenized collateral, automated but constrained credit, always-on markets, and machine-readable ownership and compliance. This is where the crypto ecosystem becomes practical rather than ideological.
Stablecoins can provide programmable dollar settlement across borders and time zones. Tokenization can represent claims, collateral, and ownership in forms that software can read and act upon. Smart contracts can execute conditional rules. Wallets can become native accounts for people and eventually agents. On-chain systems can make audit trails and permissions available in real time rather than after a chain of reconciliations.
The objective is to build guardrails into high-velocity rails. Identity, custody, permissions, collateral, auditability, compliance, and risk limits must operate at machine speed if agents are to act economically inside a trusted system.
Bitcoin’s place in this architecture is distinct. Bitcoin may not settle every agent transaction. Stablecoins and specialized rails may do much of that work. But Bitcoin remains the proof and the foundation: a scarce, globally transferable digital bearer asset outside the discretionary expansion of any one credit system. It can become increasingly relevant as neutral collateral and long-duration savings while more transactional layers of crypto evolve above it.
The architecture has layers. Bitcoin Layer 1 can serve as the scarce collateral and final-settlement anchor. Stablecoins, tokenized deposits, Layer 2 networks, and other programmable rails can handle the high-frequency velocity of a machine economy. Every agentic micro-transaction does not need to occur on Bitcoin’s base layer. The system needs a trusted monetary foundation and faster rails for continuous activity.
AI creates the need for machine-speed economic agency. Crypto provides the emerging rails. Bitcoin provides the monetary foundation and the digital store of value in a world of hypercompetition and disruption.
The Debt Market Meets the AI Capital Cycle
This collision is occurring inside a credit-backed fiat system with its own time problem. Debt finances present spending and investment through claims on future income, taxes, and output. That structure rests on confidence that tomorrow’s economy will be legible enough to underwrite promises made today.
Governments face a duration trap. They refinance long-dated fiscal obligations while AI shortens the life of the assumptions beneath them: the tax base, labor market, corporate profit pool, and durability of competitive advantage. At the same time, the physical AI buildout requires capital now, chips, compute, data centers, cooling, generation, transmission, land, and construction. Long rates reflect fiscal supply, inflation expectations, monetary policy, growth, global savings, and term premia. AI capital spending adds to the pressure by increasing the competition for capital, energy, and physical capacity. Debt is a claim on future output
I joined Morgan Stanley in 1992, just as arguably the greatest asset bubble of the twentieth century was deflating. Japan’s stock market had peaked, land prices were rolling over, and the country was beginning a journey that would define global macro for the next three decades: the slow accumulation of government debt to levels economists have repeatedly argued would be unsustainable. At the time, Japan was the outlier. Today, the government debt virus has spread across most of the developed world.
In the years following the bursting of Japan’s asset bubble, macro investors would repeatedly return to the same trade: short Japanese government bonds on the assumption that the country’s fiscal trajectory would eventually force a repricing. The trade became known as the widowmaker because the expected reckoning repeatedly failed to arrive. Japan ultimately taught an entire generation of traders how long a government that is effectively bankrupt and weak can survive without the debt condition improving.
That history matters because of what happened the last week of July. I was living in Brazil in 1998, and last week brought back memories of that year. The circumstances today are clearly different, but there were enough connections to believe it was an important macro inflection point, just like in 1998.
In June 1998, with the Asian financial crisis still spreading around the world and impacting every emerging market with a debt problem, we had a similar situation. At the same time, like today, the yen was weakening and applying pressure to a then weakening macro backdrop. The United States and Japan intervened jointly in the foreign-exchange market to support the yen. Within months, Russia defaulted, Long-Term Capital Management collapsed, and the unwind of leveraged yen-funded carry positions contributed to one of the most violent currency moves of the decade.
Fast forward to the last week of July this year: a hedge fund blow up, a new Fed Chairman losing some credibility on how hard he truthfully wanted to fight inflation with a bloated balance sheet, and then, closing out the week, the first coordinated yen intervention by the US and Japan since 1998.
Those events, and the reminder for me of 1998, are why I view last week’s intervention as something we will look back on as a contextual signal of the nexus point the world is in right now and where it is headed. I say contextual because the events occurred with global equity markets at or near record highs and earnings and profit margins growing rapidly. Credit spreads are near all-time tights. The VIX is calm. There is no obvious recession, banking panic or broad credit event forcing policymakers into emergency action. Yet the United States still concluded that the deterioration in the yen was important enough to join Japan in supporting the currency for the first time since my time in Brazil. In a market environment where most traditional measures of risk continue to appear benign, that decision stands out. The move itself is less important to me than the context in which it was made. There is no precedent for the world we are living in. This week represents exactly why my service is focused on the nexus between the aging, credit-based fiat system, AI, and crypto. For me, the last week of July was a nexus point, a moment when the collision pressures between these three forces became increasingly visible.
This gets back to the widowmaker reference. What stands out is that the timing of this nexus point coincided with the largest monthly rise in US 30-year yields since the new administration took over. It also happened to be the highest monthly yield close in over 20 years. We have learned over the last two years that their line in the sand appears to be a rise in long-term yields.
Yields have become one of the defining constraints on U.S. macro policy. When long-term yields rise materially, the move does more than tighten financial conditions. It increases the cost of servicing an already large stock of federal debt and raises the hurdle rate for private-sector investment, in particular the capital needs for the geo-politically important AI infrastructure buildout. It also pressures housing and other duration-sensitive sectors, exacerbating the K-shaped economy, and increases the amount of interest expense that must ultimately be financed through still more government borrowing. The higher yields go, the more fiscal policy and monetary policy begin to interact with each other.
We have repeatedly seen that large upward moves in long-term yields eventually generate a policy response of some kind. The response does not necessarily come through a traditional Fed rate cut. It can occur through liquidity measures and new liquidity facilities, changes in Treasury issuance, regulatory adjustments, central-bank communication and now, as we saw last week, coordination in the foreign-exchange market. The specific mechanism matters less to me than the recurring pattern: the administration has become increasingly sensitive to sustained increases in the cost of capital, and it appears to be its line in the sand. As I have said regarding the AI capex boom, we are running hot into compute scarcity. For the Fed and Treasury, we are running hot into a scarcity of tool options to fight long-term yields.
This is why the US-Japan coordinated intervention becomes particularly important. Japan is one of the world’s largest pools of savings and a major holder of U.S. financial assets. Japanese investors constantly make relative-value decisions between domestic bonds and foreign assets based on yields, currency levels and hedging costs. A rapidly weakening yen alongside rising Japanese yields and rising U.S. yields can alter those calculations significantly. At a moment when the United States needs enormous amounts of capital to finance its fiscal deficits, instability in the currency of one of its most important creditor nations is not an isolated Japanese issue.
That is why the U.S. participation in the intervention deserves far more attention than it has received. The important question is not simply why Japan wants help with a weakening yen. That is obvious. The more interesting question is why the United States decided that Japan’s currency problem had become an American problem. When both the borrower and the lender are burdened by debt, the relationship stops functioning like a normal credit system. That is the world we have arrived at now since the last time they worked together in 1998.
The rest of the market action in late July makes that question even more relevant. The Federal Reserve left markets unusually uncertain about the path of policy. Kevin Warsh has moved away from the traditional reliance on forward guidance and has indicated a greater willingness to allow markets themselves to determine financial conditions. At the same time, long-term yields were moving sharply higher. In theory, allowing the bond market to perform some of the Fed’s tightening work makes sense. In practice, the ability to tolerate significantly higher long-term yields becomes more complicated when the federal government’s interest expense is already rising rapidly. That is why the Treasury decision to intervene just two days after the Warsh comments is important, especially in the context of him recently being chosen by the administration amidst questions around Fed independence.
Then there was the extraordinary reversal in momentum and AI-related equities in July. This may not have been at the scale of LTCM, but the factor volatility rise and momentum fall was historic. The important point, in my view, is that the selloff was not driven by a corresponding deterioration in the fundamental AI story or in the broader economy. Demand for compute remains exceptionally strong and, in my words, insatiable. Hyperscaler capital spending remains elevated, backlogs remain enormous, and the underlying technological progress continues. What changed was crowded positioning, leverage and vol-controlled strategies at record gross hedge fund leverage. In a financialized world where government debt is a virus around the world and US stock market cap to GDP is over 200%, stocks, like long-term bonds, are not allowed to fall for long.
Crowded exposure, leverage and factor concentration turned a fundamentally healthy theme into the center of a violent market adjustment. That distinction matters. Market structure is going through a change: markets increasingly contain enormous pools of capital using similar data, similar risk models and increasingly similar AI-assisted analytical tools. When positioning becomes crowded, a relatively modest change in price can trigger automatic vol-controlled risk reduction across many portfolios simultaneously. The speed of the resulting move can become disconnected from the speed at which the underlying economic fundamentals are changing. LTCM took a long time to play out. The Situational Awareness fall took weeks, from a fund up hundreds of percent.
This is one of the larger changes taking place in global markets. AI is increasing the speed at which information is processed and incorporated into prices at precisely the same moment that government debt is reducing policymakers’ tolerance for large moves in interest rates and financial conditions. Those forces are becoming increasingly interconnected. Technology is accelerating market behavior while fiscal constraints are making the financial system more sensitive to the consequences of that acceleration.
The result is a market structure in which deleveraging becomes increasingly difficult for policymakers to tolerate. Governments need nominal growth to manage large debt burdens, but inflation remains high enough to constrain traditional monetary easing. Because of the debt burden, central banks have less freedom to fight sticky inflation with aggressive rate hikes, while governments have less ability to tolerate the economic damage created by substantially higher long-term yields. That leaves policymakers increasingly dependent on alternative mechanisms for managing financial conditions.
On Friday, we received another weak payroll report. At the same time, AI continues to surprise almost everyone with the speed of its exponential growth. Anthropic’s model capabilities and adoption, for example, have driven ARR growth at a pace the world has rarely, if ever, seen. Despite what your favorite economist may tell you while looking through a historical lens and assuming the old relationships still hold, something has changed. AI is already disrupting the labor market, and the rise of AI agents is only beginning.
Again, looking at the labor market contextually, it is very weak. Historically, with S&P 500 earnings growing this fast, job creation is normally robust. Right now, the six-month rate of change in aggregate payroll, combining hourly earnings, hours worked, and the number of jobs, is at its weakest non-COVID level since 2012, while earnings are growing at a post-stimulus pace. The labor force participation rate has fallen sharply this year and wages are falling. This all started at the unofficial beginning of AI agents, digital employees, with the rise of OpenClaw followed by Hermes. Economists academically try to show numbers on how AI is not causing job losses, but aggregate hours, wages and surveys show this is more about a lack of hiring while nominal GDP, revenues and earnings grow sharply.
Look at the labor market through that AI disruption lens, combine it with the late July events, and it looks less like three unrelated stories and more like different expressions of the same underlying tension. A crowded AI trade experienced a violent positioning unwind despite strong fundamentals. The Federal Reserve left investors uncertain about how it intends to balance persistent inflation against rising long-term borrowing costs. Treasury yields moved sharply higher as fiscal concerns remained unresolved. And in the middle of it all, the United States joined Japan in a coordinated effort to stabilize the yen.
Don’t read this paper as a suggestion that another 1998-style deleveraging event is imminent. In 1998, the fault line ran through emerging markets, where weakening currencies and unsustainable debt burdens ultimately required IMF intervention. The situation today is fundamentally different. This time, the United States is helping Japan manage the consequences of its debt burden at least partly because instability in Japan can feed directly back into U.S. debt markets. In other words, the intervention is not simply about helping Japan with its problem. It is also about protecting the global capital flows the United States increasingly depends on to finance its own.
That may be the most important signal from last week. Stock markets remain near record highs, yet policymakers behaved as though something in the global financial architecture required attention. The intervention suggests that the interaction among currencies, sovereign yields, and cross-border capital flows has become important enough to warrant coordinated government action even in the absence of an obvious financial crisis.
For me, this is not being driven by a hidden leverage crisis like 1998. It is being driven by the nexus between an aging, credit-backed fiat system already under pressure and the accelerating disruption of AI, including the enormous capital requirements needed to support it. The problem is that these two forces are moving at very different speeds. AI is advancing exponentially, while the financial and policy architecture being asked to fund and absorb that change was built for a much slower world.
I always look to asset prices for confirmation that we may have reached an important nexus point, and this week that confirmation showed up in gold. Gold rallied more than 7%, one of its strongest weeks since the GFC, immediately following the events of the final week of July. Almost as quickly, Bessent publicly suggested that the Federal Reserve consider expanding the FIMA repo facility, which would allow Japan to raise dollars against its Treasury holdings rather than sell those securities into the market. These are not conventional policy responses for an environment in which equities are near record highs and credit spreads remain historically tight. FIMA is not literally money printing, but economically it belongs to the growing set of balance-sheet mechanisms designed to prevent forced asset sales and preserve liquidity when stresses emerge. At a minimum, it is a verbal bazooka indicating they are scared.
That is why I view gold’s move as more than a reaction to weaker payrolls or shifting Fed expectations. Macro participants are recognizing that the debt overhang is increasingly forcing policymakers toward some version of the same answer: keep the system running hot while developing additional hidden liquidity tools to manage the consequences. Gold is the asset class most naturally positioned to ask whether maintaining the stability of the sovereign debt system will ultimately require more liquidity, more financial repression, and a continued tolerance for nominal growth and inflation running hotter than the old framework would have allowed.
As Lyn Alden has argued in a different context, nothing stops this train. Governments are trapped by the size of their debt burdens and, in the US case, its deficit. They need nominal growth, productivity and asset appreciation to outrun the mathematics of the debt.
The institutional details reinforce that conclusion. Treasury’s willingness to discuss raising the relevant FIMA cap in order to facilitate Federal Reserve participation in the dollar-yen operation suggests a degree of coordination between Treasury and the Fed that may be greater than investors appreciate. It does not mean the two institutions have identical objectives, but it does highlight how difficult it has become to separate monetary policy, fiscal policy and financial-stability policy when sovereign debt levels are this large.
That has an important implication for the Fed. If Treasury and the Federal Reserve are increasingly operating within the same constraint set, large deficits, rising interest expense, inflation that remains too high for unrestricted easing and a financial system that cannot easily absorb uncontrolled deleveraging, the range of genuinely hawkish policy outcomes becomes narrower. A Fed that allows long-term rates to perform the tightening may discover that the fiscal consequences of those higher rates eventually force policymakers back toward intervention.
The next phase of that collision is likely to bring renewed fears of currency debasement. Governments are carrying debt burdens and fiscal deficits that become harder to manage as long-term interest rates rise. Interest rates are rising because governments are running hot into scarcity in the global AI race while the capital needs to fund it grow. It is unlikely the actions between Japan and the US will stop the pressure. Dollar Yen has become a new pressure point for the market to watch. At the same time, they cannot easily tolerate the kind of deleveraging that would normally accompany tighter financial conditions. The path of least resistance therefore continues to point toward liquidity: new facilities, balance-sheet mechanisms, financial repression, and ultimately policies designed to keep nominal growth running faster than the debt burden. Gold’s move this week may be the market’s first acknowledgment that the solution to the debt problem will increasingly look like some form of debasement.
AI will only intensify the tension. The disruption in the labor market is still in its earliest stages, and the rise of AI agents is only beginning. The first half of the year investors focused on the infrastructure needs to support those agents.
In the second half, I believe the adoption and actions of the agents become the important investment thesis.
Over the next twelve months, I expect agents to move rapidly from tools that assist humans to systems that increasingly act on their behalf. That means more productivity, but it also means more pressure on employment, wages, tax receipts, and the political response required to manage the transition. The economic system will simultaneously be asked to finance unprecedented investment in compute infrastructure while adapting to a technology capable of reducing the need for human labor across an expanding number of industries.
The next step is where this becomes even more interesting. Consumer agents are about to enter the financial system. They will search, negotiate, purchase, move money, allocate capital, and transact at a speed and frequency humans never could. That should increase the velocity and volume of economic activity, but it also creates a new problem: the financial guardrails of the analog economy were designed around human beings making decisions, not billions of autonomous software agents conducting transactions continuously.
That brings me to the next intersection in the AI Macro Nexus: crypto.
If AI is creating a digital economy increasingly populated by autonomous agents, then that economy will require digitally native money, collateral, settlement, identity, and financial infrastructure. At the same time, if the response to the debt burden of the existing fiat system increasingly requires liquidity creation and currency debasement, then scarce digital assets become more relevant, not less. These two forces are approaching each other from opposite directions.
That is why I am spending more time now on this next phase in my videos and writing. The first phase of the AI Macro Nexus was understanding the physical infrastructure required to create intelligence. The next is understanding what happens when that intelligence begins acting autonomously inside an aging financial system that was never designed for it. This bec
Executive Summary
AI is compressing the lifespan of every corporate advantage, and the market is already pricing it: in July, volatility inside the equity market hit all-time highs while Bitcoin’s volatility sat at cycle lows, and this paper argues those two facts are the same story.
This is a long paper because the argument required a market event before it could be seen clearly. July supplied it, so pour the coffee and settle in.
Two volatility readings crossed in July. Factor volatility, the turbulence inside the equity market’s most crowded AI trades, exploded to all-time highs. Bitcoin’s realized volatility spent the same month at cycle lows, absorbing a double-digit drawdown that in any prior cycle would have left it vulnerable to risk-asset weakness and sent its volatility past 80%. Winners versus losers in technology risk assets saw their volatility rise to levels higher than during the dot-com bubble and the GFC, while Bitcoin volatility did not move and the asset finished higher for the month. The asset built on forecastable cash flows turned violent while the asset with no cash flows went quiet. This paper is my attempt to explain why.
The short version: AI is compressing investment time. Products get built faster, competitors arrive sooner, and the duration of every moat, the input no DCF prices carefully, is shrinking. The market’s doubt has climbed the entire stack in a year: software companies, then the model labs, and now the hyperscalers, questioned at the very moment they carry roughly $1.7 trillion in forward demand and their customers reserve capacity years in advance. Kimi K3 showed frontier capability now spreads in days, so even historic revenue growth at Anthropic and OpenAI buys no immunity. Jevons Paradox says cheaper intelligence explodes consumption. What I call the Intelligence Competition Paradox says it melts ownership. Both are true at once.
That leads to double debasement: fiat printing debases the money, while AI printing debases the moat. The paper ends with a four-layer investment map: own the physical bottlenecks, own the distribution layer that wraps intelligence in trust, re-underwrite every moat against abundant cognition, and hold exposure to scarcity that no press can reach, because liquidity is an option on time.
No company is safe. The volatility market figured that out first.
AI Is Compressing Investment Time and Forcing a New Search for Value
Two volatility readings crossed in July, and the crossing is the strangest fact in markets right now.
The first reading came from inside the equity market. Momentum suffered one of the most violent reversals in the history of factor data, and factor volatility, the turbulence hiding beneath the calm indexes, exploded to all-time highs. The epicenter was the AI trade, the most crowded and most analyzed set of positions in the world.
The second reading came from the asset institutional investors were taught to dismiss as too wild to own. Bitcoin’s realized volatility spent the same month sitting at cycle lows. Its 365-day realized volatility ended July at 37%, close to multi-year lows, while absorbing a double-digit drawdown that in any prior cycle would have sent volatility screaming past 60%. Through July’s storm, it barely stirred while technology momentum factor volatility soared past 100.
Hold those two facts side by side. The asset class built on forecastable cash flows turned violent. The asset with no cash flows at all went quiet. Volatility is the market’s live estimate of uncertainty, and the market just told us it is becoming less certain about the most studied companies on earth and more certain about the asset it spent fifteen years calling a casino.
Markets do not produce a crossover like that by accident. Something deep is being repriced on both sides, and this paper is my attempt to name it.
Start with the equity side of the cross. The hyperscalers reported some of the strongest revenue and backlog numbers ever printed by public companies. Anthropic and OpenAI posted growth curves that enterprise software has never seen. And the market’s response was to question all of them. Not the laggards. The winners.
There is a pattern here, and it has been moving up the AI stack for more than a year. Software companies were the first to be re-underwritten as investors questioned the durability of their products and terminal values. Then it spread to any sector whenever Anthropic released a new tool. The anxiety then reached the hyperscalers, where declining free cash flow, unprecedented CapEx, and rising CDS yields raised concerns about the cost of maintaining AI leadership. It has now reached OpenAI and Anthropic: even historic ARR growth offers limited comfort when rapidly improving open-source models can challenge the duration of their advantage. Every layer once viewed as protected is now being forced through the same re-underwriting process.
I think the market is telling us something it doesn’t yet have words for: AI is compressing economic time. Products get built faster. Competitors arrive sooner. AI-native companies are growing with fewer employees. Advantages that took a decade to construct can be pressured in a quarter. When the clock speeds up, the confidence interval around every terminal value widens, and investors start asking a question that has nothing to do with next quarter’s earnings.
When intelligence becomes abundant, what remains scarce, liquid, and believed in?
That question is where this paper ends, and it is where the volatility crossover finally gets resolved. The journey starts in July, with the unwind.
July Was a Warning About Economic Time
Every violent market episode teaches one lesson if you’re willing to look past the price action. July’s lesson was about duration mismatch.
The investors caught in the unwind were not wrong about AI. Many of them will eventually be proven right. They were wrong about time. They held views that resolve over years inside portfolios that get marked every day, margined every week, and redeemed every quarter. The Situational Awareness episode was the cleanest example: a thesis about the trajectory of machine intelligence, funded by capital with the patience of a mayfly.
When factor volatility finally exploded, hitting levels we have never recorded, the long-term view offered zero protection. Leverage converted uncertainty into forced selling, and forced selling converted a positioning event into a narrative event. That second conversion is the dangerous one.
Here is how it works. Prices fall first. Then investors go looking for a story that fits the tape, and the AI bear case is a fully stocked shelf: circular financing, runaway CapEx, missing ROIC, chip obsolescence, open-source erosion, power delays, vanishing free cash flow. Pick any two. The correction becomes proof of the fear, even when the honest explanation is that too many people owned the same thing with borrowed money.
I traded through 1998 and the LTCM unwind. I watched brilliant long-term theses die of short-term causes. July was that movie again, updated for the AI era, and it previewed the regime we now live in: a technology compounding exponentially, held by humans who think linearly, funded by capital that needs liquidity daily. That collision will happen again. The unwind wasn’t the story. It was the trailer.
AI Is Compressing Investment Time
The human brain is a linear extrapolation machine. We take the last few years, draw the line forward, and call it a forecast. Every DCF model on every desk is a monument to this habit: growth fades gently, margins mean-revert politely, and the moat erodes on a civilized schedule measured in decades.
AI does not respect the schedule.
Model capability now improves in months and soon in days. The price of a unit of intelligence falls in quarters. An open-weight release crosses the planet in a weekend. A five-person team can ship a product, find customers, and attack an incumbent’s margins before that incumbent finishes its annual planning cycle. The gap between invention and imitation, which is the gap where all excess returns live, is closing in front of us.
This is what I mean by the compression of investment time. Nothing about a DCF breaks mathematically. What breaks is the input nobody prices carefully: the duration of the moat. A company can beat every quarter and still be repriced brutally, because the value was never in the next eight quarters. It was in years eleven through thirty, and those years just got harder to underwrite.
So the process has to change. My father taught me to handicap rather than predict, and I have never needed that lesson more than now. Investing in this environment requires Bayesian discipline. You begin with a distribution of outcomes and update it as the evidence changes. Every model release, backlog number, and pricing change moves the probabilities. Positioning is evidence too: when other investors begin bragging about owning the same trade, the fundamental outlook may be unchanged, but the odds embedded in the price have shifted. A view that remains fixed through changing evidence and increasingly crowded positioning has hardened into a story.
Stories are how July happened. Distributions are how you survive the next one.
The Hyperscaler Anxiety and the Math Investors Are Missing
For fifteen years, owning Microsoft, Alphabet, Amazon, and Meta was the closest thing public markets offered to a free lunch. Their scale was the safety. Now the same scale is the anxiety, because staying in the AI race requires spending at a magnitude with no precedent in corporate history.
The bear case is not stupid. These companies are converting oceans of operating cash flow into chips, memory, land, steel, and gigawatts, and the honest underwriting question is whether that capital becomes productive capacity or a very expensive museum of 2026-era silicon. Fear of the second outcome is why the stocks trade the way they do. Nobody, including them, knows what the future holds once we hit AGI, ASI, and a world of humanoids with superintelligence.
But look at what the fear is ignoring today. This earnings season, the demand side of the ledger did not wobble. It accelerated.
Microsoft: $90 billion in quarterly revenue, up 18%, with Azure growing 43% and commercial remaining performance obligations reaching $678 billion, up 84%, and still up 25% with OpenAI stripped out. Alphabet: revenue of $119.8 billion, up 24%, with Google Cloud up 82% and its operating margin expanding from 20.7% to 35.6%; management flagged that growth accelerated meaningfully even excluding TPU system sales, and the cloud backlog hit $514 billion, with just over half converting inside 24 months. Amazon: $200.6 billion in revenue, AWS up 37% for its fastest growth in 18 quarters, and an AWS backlog that jumped from $364 billion to $496 billion in a single quarter, with most 2027 capacity already reserved and commitments reaching into 2028. Meta: revenue up 28%, advertising up 27%, impressions up 14%, and price per ad up 12%, with its compute pointed inward at an ecosystem management believes is generating attractive returns today.
Add it up and Microsoft, Alphabet, and Amazon alone are carrying roughly $1.7 trillion of contracted forward demand. The definitions differ and the conversion timing differs, but the direction does not. Customers are reserving intelligence capacity years in advance, the way airlines reserve aircraft.
Andy Jassy then did something CEOs rarely do: he showed the math. A data center takes about two years of investment before it opens and then earns for roughly 30 years. The AI servers inside it pay for themselves in under three years and keep producing profit for two to three more. Be precise about what that means, because the bears won’t be: the building and the silicon are two different underwriting problems. The shell is a 30-year asset; the servers are five-to-six-year assets on a refresh treadmill. Jassy’s claim covers the harder problem, the silicon, and his answer is that it pays back before it depreciates. And even after lifting 2026 CapEx to $220 billion, he says AWS still cannot build fast enough for the demand it can see.
That is the tension defining this market. As an equal-weight group, Meta, Microsoft, Amazon, and Google finished July up only 3% YTD. The most successful companies in history are being questioned at the exact moment their customers are demanding more capacity. Concerns about declining free cash flow, rising CDS yields, and uncertain returns on invested capital have come to dominate the narrative, even as revenue accelerates, backlogs expand, and management teams describe demand running ahead of supply. July’s unwind changed the positioning and therefore changed the odds: the fundamental risks remain, but the price and crowding around those risks have shifted. The spending may become the deepest moat ever dug or an entry fee that keeps rising. The uncertainty is the truth.
The First Scarcity Trade: Compute
Strip away the noise and the AI economy reduces to one imbalance: intelligence demand compounds at the speed of software, and intelligence supply arrives at the speed of construction.
Demand first. An AI agent is a worker that never sleeps, never unionizes, and spawns copies of itself. It writes code, tests the code, researches the market, drafts the memo, answers the customer, and calls other agents to do the parts it can’t. Every capability improvement expands the set of tasks worth automating, and every newly automated task is a permanent new stream of inference demand. The demand curve doesn’t shift right. It shifts right and steepens.
Supply, meanwhile, is hostage to the physical world: fab cycles, transformer lead times, interconnection queues, permits, concrete, and the finite number of electricians in North America. You cannot download a substation.
This is where the speed of code meets the speed of steel, and the collision creates the first scarcity trade of the AI era. Compute, memory, networking, optics, generation, transmission, cooling, electrical gear, data-center shells. Everything on the steel side of the collision gets more valuable as everything on the code side gets cheaper.
There is a beautiful recursion buried here. The bottleneck’s eventual solution is the bottleneck itself: agents will one day compress data-center design, grid engineering, and permitting, but building those agents requires the very compute we don’t have enough of. Scarcity is funding the tool that ends the scarcity, which tells you the shortage resolves eventually and also tells you it doesn’t resolve soon. 2026 has been the year investors embraced scarcity.
Kimi K3 and the Arrival of Intelligence Abundance
Every regime has a moment when the future stops being theoretical. For intelligence abundance, that moment was Moonshot releasing Kimi K3: 2.8 trillion parameters, open weights, frontier-level coding and agentic capability, free to download. The scarcest input of the new economy was suddenly being given away. This may be the most important connection to Bitcoin as an asset.
Two consequences followed, pointing in opposite directions.
For infrastructure, K3 was rocket fuel. Cheaper intelligence means more viable use cases, more use cases mean more inference, and more inference means more of everything physical. The open-source release that terrified equity investors was, mechanically, a demand shock for compute.
For ownership, it was a grenade. Anthropic had just put up numbers that should have ended every argument: a run-rate near $9 billion at year-end 2025 growing past $47 billion by May 2026. OpenAI was compounding from $20 billion into the mid-twenties. These are the fastest commercial ramps in the history of enterprise technology. And within days of K3, the market’s question was not “How big can this get?” but “How long can they charge for what China now gives away?”
Read that carefully, because it is the whole thesis in one sentence: the biggest revenue winners of the AI era got the same treatment as the hyperscalers. Growth bought them no immunity. Only duration matters now, and duration is exactly what nobody can prove.
My handicapping: the open-source threat is real but aimed at the wrong target. K3 competes for AI-native startups and technical teams that can run their own stack. The Fortune 500 does not want weights. It wants a product: permissions, governance, audit trails, uptime guarantees, support contracts, indemnification, and an interface a compliance officer can love. Anthropic and OpenAI are building that wrapper as quickly as they build models, and $70 billion of combined run-rate says enterprises are paying for the package, not the parameters.
But enterprise preference for a managed product does not make incumbents themselves safe from disruption. In many ways, the speed of progress makes the enterprise adoption problem harder. A startup can choose a model, redesign its workflow, discard the architecture six months later, and begin again. A public company has customers, regulators, boards, legacy systems, cybersecurity obligations, procurement processes, and reputational risk. Every decision must survive committees that know the technology may be obsolete before the implementation is complete. The rational fear of choosing the wrong model, architecture, or vendor can freeze the organization into choosing nothing at all.
That hesitation creates its own risk. While established companies debate whether to build, buy, fine-tune, use open source, or commit to a closed platform, AI-native competitors are building their companies around the assumption that intelligence is abundant, software is disposable, and workflows can be redesigned continuously. The incumbent is trying to attach AI to an existing organization. The startup is designing the organization around AI. In a technology cycle moving this quickly, governance protects the enterprise, but excessive caution can become an accelerant for disruption. The same inertia can also drive the most ambitious employees toward companies where they can build without waiting for institutional permission.
This is not merely an operating problem. These enterprises are also stocks and assets held throughout people’s portfolios, retirement accounts, pensions, and index funds. Many of them have been among the most successful investments of the past fifteen years, and their past consistency has encouraged investors to treat future cash flows as unusually durable. But AI introduces uncertainty precisely where traditional valuation models are most sensitive: the terminal value.
A discounted cash-flow model can accommodate slower growth, temporary margin pressure, or higher capital spending. It becomes far less reliable when the competitive structure of an industry may be rewritten before the forecast period ends. If an incumbent delays too long, chooses the wrong architecture, becomes dependent on a vendor, or loses its economic advantage to an AI-native competitor, the problem is not simply that next year’s earnings estimate is too high. The duration and defensibility of the entire future cash-flow stream may have been misjudged.
That is why AI can create multiple compression even when current earnings remain strong. Investors are not necessarily questioning what these companies earn today. They are questioning how confidently anyone can capitalize those earnings ten or twenty years into the future. The companies that dominated the last fifteen years may still dominate the next fifteen, but the probability distribution is wider, and a wider distribution around terminal value should command a lower valuation multiple.
Still, K3 moved my distribution, and it should move yours. It proved frontier capability now diffuses in days, not years. The labs can keep growing at historic rates while the market rationally shortens the duration it will pay for. Explosive demand, uncertain ownership. Str
TLDR
: Corporations as we know them are about to undergo radical transformation.
We are at the precipice of the
Organizational Singularity
. Already 70% of CEOs admit they have a high-margin line of business that two people with AI agents could replicate in 60 to 90 days. The company as we know it is about to undergo the most radical restructuring in 200 years.
Last week, my partner and Moonshots Mate
Salim Ismail
delivered a two-hour masterclass to our Abundance360 community on what he calls the Organizational Singularity. Salim has spent 15 years advising Fortune 500 companies on innovation. He has sat in the boardrooms of 200 of the Fortune 500. He co-authored the Exponential Organizations framework with me. And what he presented last week was the most important business thesis I have heard in a decade.
I am sharing it here because it is too urgent to keep inside our Abundance and ExO community. Every CEO, founder, executive, and employee needs to understand what is coming. The technology that makes this possible is not theoretical. It exists today. And the forcing function is existential.
THE 70% QUESTION THAT SHOULD KEEP EVERY CEO AWAKE
Salim asks every CEO he works with a simple question:
“is there a high-margin line of business in your company that two people with AI agents could replicate in 60 to 90 days?”
70% of CEOs answer yes. That means that seven out of ten CEOs are running companies with a profit center that is easily and rapidly disruptable.
Beyond a competitive threat, this is an extinction level event. The two people do not need to be in your industry. They do not need your supply chain. They do not need your sales force. They need an AI agent stack, an internet connection, and 90 days.
THE INTELLIGENCE STACK: HOW AI NATIVE COMPANIES WORK
Salim has been building this framework with engineers from OpenAI and Anthropic. It is not theoretical. It is a working architecture. Here is how it works.
An AI-native company runs on an intelligence stack with five layers, each staffed by AI agents:
Sensing Layer
: Agents scan the environment continuously. Press releases, regulatory filings, market data, competitor moves. They bring information back in real time.
Interpretation Layer
: Agents analyze what the sensing layer found. Is this a threat? How big is the market? What are the implications? Options are generated.
Decision Layer
: Agents evaluate options and recommend action. Ignore? Counter? Experiment? Each decision goes to a human for yes/no approval.
Orchestration and Execution Layer
: Agents carry out the decision. Lease the trucks. Launch the test. File the paperwork. Done in hours, not weeks.
Learning Layer
: Agents analyze what worked and what did not. Next time, the loop runs faster.
The C-suite is involved at every layer, but only to hit yes or no. The humans are above the loop, not in it. In a traditional company, this cycle takes weeks or months. Salim says in an AI-native company it takes hours or days. The military calls this the OODA loop: Observe, Orient, Decide, Act. An AI-native company runs OODA loops at machine speed with human judgment at the checkpoints.
Wrapped around the entire stack is a governance band. Every agent has an evaluation suite. Every action is logged and traceable. Rollback capability exists if an agent goes off track. A human review queue ensures accountability. These are not autonomous agents doing whatever they want. They are junior employees that need supervision, correction, and guidance. The governance layer is what makes the system safe to deploy.
HOW TO GET THERE: THE EDGE STRATEGY
Here is the key issue that
trips up every CEO
who hears this. You cannot transform your existing company from within. The immune system will attack any significant changes you attempt to make.
Salim has seen it 200 times. The CFO says no. The CIO says you are crazy. The head of innovation comes back with arrows in their back. Every big company is architected for efficiency, repeatability and predictability, not disruption. McDonald’s exists to deliver the same Big Mac at the same quality in every location on Earth. If you try to introduce something disruptive, you get crushed. It does not matter how nice you are.
The solution is what Salim calls the
edge strategy
. Here’s how it works:
Build a digital twin of your company at the edge, still inside your firewall.
The digital twin report directly to the CEO.
You begin by picking two high-throughput workflows and rebuild them using the intelligence stack.
You run these in parallel with the old system.
When the new version outperforms the old, you deprecate the old.
Then you move the next workflow. Then the next.
Over 8 to 20 months, you grow this new AI-native operation at the edge until it replaces the legacy core.
This is the digital version of what Lockheed did with its Skunkworks, what Nestle did with Nespresso, and what Apple (Steve Jobs) did with the Mac.
The edge strategy is not new. What is new is that AI agents make it 100x faster.
THE 100X PERFORMANCE LEAP
Salim’s calculations, based on the pilot programs he is running with 10 companies right now, show that AI-native organizations will be approximately 100x more performant than today’s companies.
If you process 1,000 leads per month today, you will process 100,000. If you handle 1,000 invoices per month, you will handle 100,000. And you will do it with about 20% of your current headcount. One fifth of the people. One hundred times the throughput.
Before you panic about unemployment, both Salim and I believe that this strategy will also spawn five times as many startup companies. They will be smaller, more nimble, and radically more performant. The economy does not shrink. It fragments and then explodes.
“The big legacy company does not survive.
The small AI-native company does.”
This is already happening. Call centers went from human BPO to chatbot-assisted to fully AI-native in three years. Content management went from outsourced agencies to AI-assisted tools to fully AI-native in two years. Sales, logistics, finance, and every other domain are next.
WHAT SURVIVES AND WHAT DIES
In the AI-native organization,
here is what survives
:
Your MTP (Massive Transformative Purpose)
survives as an encoded protocol. It is the constitution that guides the agents.
The legal shell of the company survives
. Accountability, liability, fiduciary duty. The firm as a container for data and learning loops.
Proprietary intelligence survives
. Your data, your learning loop, your proprietary models trained on your data. This is your moat.
Human judgment survives
. The decisions that require intuition, ethics, and context. The things AI agents cannot do well yet.
Here is what dies:
The static org chart.
In an AI-native company, the org chart is fluid. It changes when you add a line of business. It is a protocol, not a document.
Static planning.
The five-year plan is dead. Strategy becomes a continuous exercise run through the agentic layers, not a quarterly or annual exercise.
Middle management as a coordination layer
. We estimate that middle management collapses by 60 to 80% in this new world.
Switching costs
. When you can swap models in minutes, loyalty must be earned continuously.
Coase’s Law, the foundational economics principle that says companies exist because coordination costs are cheaper inside the firm than outside, has been superseded. AI agents have made coordination costs essentially zero. The reason companies exist is changing. The shape of companies is changing. The size of companies is changing. The only question is whether you are doing the changing or having it done to you.
WHAT THIS MEANS FOR YOU
If you are a CEO
: Score yourself on the 70% question. If you have a high-margin line that two people with AI agents could replicate in 90 days, you have 90 days to start building your edge strategy. Not next quarter. Now.
If you are an entrepreneur
: The 70% stat is your opportunity map. Find the high-margin line of business in a legacy company. Build it with two people and an agent stack. 90 days to disruption.
If you are an investor
: Companies with proprietary data and proprietary learning loops are the survivors. Companies with static org charts and five-year plans are the targets. Bet on the edge.
If you are a parent
: Your kids will not work in companies that look like the ones we work in today. They will either build AI-native companies on their own or work in them. Both are better outcomes than the legacy alternative.
If you are an employee
: The white-collar drudgery is being automated. The judgment, intuition, and experience you bring are what survive. Invest in the skills that agents cannot replicate.
To a future of abundance,
Peter H. Diamandis, MD
TLDR
: The tech industry has a trust problem here in America, and it is about to become a survival problem. Dario Amodei called it a crisis of trust. Sam Altman paused training because safety could not keep up. The public is not wrong. The question is what tech companies do about it. I asked my community on X this week, and the best answer came from a follower named Farzad: “prove out the abundance thesis in the most visible areas. Health. Housing. Education. Cost of living. Here is what that means”.
Yesterday I posted a question on X: what would you recommend tech companies do in order to regain public trust? The responses told me everything I needed to know about where people are right now.
The most liked response, from Farzad, cut straight to the bone:
“Prove out the abundance thesis in the most visible areas. Health. Housing. Education. Cost of living. Not messaging. Not PR. Not safety pledges. Actual results that people can see in their daily lives.”
Another responder said: “
make trust unnecessary”
. Give people ways to verify instead. A third listed every fear: “an intelligence we do not understand, jobs eradicated with no plan, communities drained of water and filled with noise.”
These are not fringe views,more so mainstream, and the tech industry is not listening.
THE TRUST CRISIS IS REAL
71% of Americans oppose data centers being built in their community. Think about that. More Americans oppose a data center than oppose a nuclear plant in their backyard. The same data centers that power the AI revolution. The same data centers that every tech company is spending hundreds of billions to build.
The public does not want them.
Dario Amodei, CEO of Anthropic, said this week that the public’s negative view of AI stems from a deeper crisis of trust.
Not from his risk warnings.
Not from dystopian science fiction. From a fundamental breakdown between what the tech industry promises and what the public experiences. He said the most accurate criticism of AI companies is that they have not delivered on their big promises to benefit the world.
That, he said, is on them.
Sam Altman paused OpenAI’s frontier reinforcement-learning training because capabilities were outpacing safety systems. The first time a leading lab voluntarily slowed down because it could not guarantee the safety of its own models.
The trust gap is not theoretical. It is operational. Texas Governor Abbott ordered an audit of all data center requests. Pennsylvania’s Governor Shapiro did the same. Both were the most pro-data-center politicians in America. Both flipped because their constituents demanded it.
And the 71% opposition is not about AI safety. Nobody cares about alignment. They care about affordability, wages, and watching tech executives get super rich while they cannot make ends meet. The backlash is economic, not philosophical.”
The public feels powerless, and showing their anger and pushback by stopping data centers may be only power they can express short of a revolt (aka firebombings).
WHY TRUST BROKE
The public does not distrust tech because they do not understand it. They distrust tech because of what they observe happening:
They see AI lab leaders publicly warning that 50% of entry-level knowledge workers will lose their jobs. When that message is amplified on the headline news, the public hears: you are coming for my job. The labs created the fear. And today’s politicians are responding to that fear.
The public sees AI models that escape containment. OpenAI’s model hacked its way out, attacked Hugging Face, and hacked back in. The public reads this and thinks:
these things are out of control.
They see closed models that cannot be inspected. When a lab says ‘trust us, the model is safe’ but obfuscates the thinking tokens so nobody can verify what it is actually doing,
the public hears the same thing they heard from tobacco, from oil, from chemicals: trust us, we are the experts.
They see tech leaders going from billionaire to trillionaire while the minimum wage barely moves. The current generation of tech billionaires (perhaps other than Elon, but he has his critics) are not aspirational figures the public looks up to. They are the people the public blames for the gap between the stock market hitting records and their own paycheck staying flat.
The public is told by the media that data centers are damaging their communities. Water use. Power consumption. Noise. Land. (Even if these facts can be proven false, here it enough times you accept it and amplify it).
The tech industry’s response to all of this has been: “
Trust us.
We are working on safety. We are working on alignment. We are committed to responsible AI.”
The public has heard this before. From the oil industry. From the chemical industry. From the tobacco industry.
Trust us is not a strategy
. It is a delay tactic. And the public knows the difference.
THE ANSWER: PROVE IT
Farzad’s response on X was the best I received. Prove out the abundance thesis in the most visible areas. Health. Housing. Education. Cost of living.
He is right. The tech industry will not regain trust by talking about safety.
“The Tech industry will regain trust by delivering results that people can feel. A cancer diagnosis that used to take weeks, delivered in minutes by AI. A house that used to cost $400,000, 3D-printed for $80,000. A tutor for every child on Earth, free. An electric bill that dropped 50% because AI optimized the grid.”
Dario Amodei said it himself: the thing that will work is actually curing cancer, not glitzy marketing. His father died of Hepatitis C only years before curative antivirals arrived. He knows that trust comes from delivering cures, not from PR campaigns. If Anthropic starts curing diseases, no regulator will touch them. Not because they are too powerful. Because they are too valuable.
This is the trust strategy that works. Not safety pledges. Not alignment research papers. Not congressional testimony. Visible, measurable, life-improving results delivered at scale to ordinary people. The tech industry needs to show the public that AI is not a threat. It is a gift. And the only way to show that is to give the gift.
THE ABUNDANCE PROOF POINTS
Here are the
proof points the tech industry must be building, right now
, and talking about louder than anything else:
100x Better Health
: AI designed protein binders with 22-35% success rates, beating the human baseline of 10-15%. Claude analyzed raw NMR data in 25 minutes, matching a contract lab that takes days. mRNA cancer vaccines succeeded in late-stage melanoma trials. These happened this month.
Make healthcare 10x cheaper and 10x better for the average American.
It can happen, it must happen and the government needs to enable and get out the way of it happening.
100x Education
: A world in which every child, whether the son and daughter of a billionaire or the poorest child in the slums, has access to equal and unparalleled AI tutors. AI tutors that adapt to each child’s learning style. That knows your child’s favorite movie star, sport and colors, delivering a highly personalized, gamified, compelling education. The cost of the best education on Earth, trending toward zero. Every child gets a personal tutor that never gets tired and never gets frustrated.
The best education in the world, available equally to everyone for free.
Cost of living
: The price of intelligence has collapsed by 428x over 6 years, from $60 per million tokens in 2020 to $0.14 today. When intelligence is free, every service that depends on intelligence gets cheaper. Legal advice. Medical diagnosis. Financial planning. Tutoring. All trending toward zero marginal cost.
Energy
: AI is forcing the biggest investment in clean energy in history. Nuclear fission restarts. SMRs. Fusion. Solar plus batteries at $6 per watt vs nuclear at $15. The AI energy bottleneck is solving the clean energy problem as a side effect.
When a data center gets built in your community, it should be mandated that the price of community energy drops by a significant amount.
Food & water
: AI-optimized agriculture. Precision irrigation. Lab-grown proteins. The same technology that trains models on data can train models on crop yields, water usage, and supply chain efficiency. Let’s make foods healthier, cheaper, and more available, enabled by AI.
Let people know that it’s the miracle of exponential tech that has cut their food costs by 50%.
Teach Entrepeneurship:
Let’s show every high school and college student how to find a problem worth solving and how to build a company to solve that problem that earns them a living.
Let’s give today’s youth
agency
over their future.
Each of these is a trust-building proof point. Not because they sound good. Because they are measurable, visible, and delivered to ordinary people. The public does not need to understand transformer architecture. They need to see their medical bill go down. They need to see their child get a tutor. They need to see their energy bill drop.
MAKE TRUST UNNECESSARY
The second-best response on my X post came from Concordium:
make trust unnecessary
. Give people ways to verify instead.
This is the transparency argument, and it is more powerful than it sounds. If AI models are safe,
prove it with open evals
. If data centers are not draining water,
publish the water usage data
in real time. If models are not biased, show the test results. If jobs are not being eliminated,
publish the hiring data
.
The tech industry operates on a model of trust us, “we are the experts”. That model is dead. The public has been burned too many times.
“The new model must be: here is the data, verify it yourself.”
Open evaluation suites. Real-time environmental monitoring. Published safety benchmarks. Third-party audits. The technology to make all of this transparent already exists. The industry just has not deployed it because it requires admitting that the public’s concerns are valid.
The closed labs say their models are safe, but you cannot see how they think. The thinking tokens are obfuscated. You have to take their word for it. Open models let you see the reasoning in real time. Which is more trustworthy: a system you can inspect or a system you have to trust? The answer is obvious. And the public knows it.
WHAT THIS MEANS FOR YOU
If you are a tech CEO
: Stop talking about safety. Start shipping abundance. Your trust problem is not a messaging problem. It is a product problem. Build something that makes a person’s life measurably better, and the trust follows. And stop doom-marketing. The fear you create becomes the regulation that constrains you.
If you are an investor
: Fund the companies that are proving the abundance thesis in health, housing, education, and energy. These are not just good investments. They are the only investments that will restore the social license to operate that the tech industry is losing.
If you are an entrepreneur
: The biggest opportunity in tech right now is not another model. It is an application that delivers a visible, measurable improvement to an ordinary person’s daily life. Build that. The trust problem becomes the market opportunity.
If you are a parent
: Your kids will inherit a world where AI can cure disease, educate every child, and lower the cost of living. The tech industry’s job is to deliver that world fast enough that the public trusts it. Your job is to demand it. Your job is also to keep your kids optimistic about the future!
If you work in tech
: Ask yourself every day: is what I am building making someone’s life measurably better? If the answer is no, you are part of the trust problem. If the answer is yes, you are part of the solution.
To a future of abundance,
Peter H. Diamandis, MD
TLDR:
AI is eating electricity faster than we can build the grid. The bottleneck today isn’t cost; it’s poles, wires, and permitting. Solar plus batteries is the fastest path to power today, but gas turbines are sold out 7 years ahead and nuclear’s comeback rides on SMRs and fusion. The race to a terawatt is the defining infrastructure story of the AI age. Here’s the full picture from my conversation with Ramez Naam.
Last week on Moonshots, I sat down with Ramez Naam, a dear friend of nearly 20 years and my go-to authority on all things energy. Ramez is a founding faculty member of Singularity University, partner at Planetary VC, author of the Nexus trilogy, and one of the top five forecasters of solar costs in the world. He gave us an epic masterclass on what he calls ‘the innermost loop’: energy. Here is what you need to know that Ramez taught us…
1. AI IS POWER HUNGRY (BUT POWER ISN’T THE COST)
A 1-gigawatt data center costs roughly $50 billion to build. $35 billion of that is chips. The 5-year energy cost? It’s trivial next to the capex. This flips the usual intuition on its head.
If you tell OpenAI or Anthropic, ‘We can give you power at twice the cost tomorrow,’ they’ll take it.
Energy is the BOTTLENECK, not the cost line
. The AI labs are racing to build the biggest models, and every month of delay costs them more than a decade of cheap power would save.
Energy is the BOTTLENECK, not the cost line.
Chart 1: The gap between projected GPU power demand and grid buildout. Source: Ramez Naam, Moonshots podcast.
Data center electricity could reach 20% of US consumption by 2035, according to EPRI. Globally, we’re looking at 1,050 TWh by 2026, more than the entire country of Japan uses today. And that’s the conservative scenario.
Chart 2: US data center electricity as a share of total consumption. Source: EPRI, IEA.
2. THE GRID IS THE BOTTLENECK TODAY
Interconnection queues went from 15 months twenty years ago to 45 months today. In ERCOT (Texas), the fastest grid in the US, a new request for hundreds of megawatts means ‘good luck getting power before 2031-2032.’
Here’s the uncomfortable truth: poles and wires have NOT become an exponential technology. Everything else in tech doubles and halves on a predictable curve. Transmission lines don’t.
“Poles and wires have NOT become an exponential technology.”
71% of Americans oppose data centers in their area, a higher number than oppose nuclear plants in their backyard. The NIMBY problem is real, and it’s slowing everything down.
But there’s a solution emerging: interruptible loads. Battery-buffered data centers that charge off-peak and can be curtailed when the grid is stressed. ERCOT passed this rule in June 2026. FERC sent letters to 6 other grids to adopt it. Ramez’s company Agentic has 10GW of qualifying sites. Interruptible status cuts interconnect time from 5-7 years to 12-18 months.
3. SOLAR + BATTERIES: THE FASTEST PATH
Solar went from $100 per watt in 1975 to 8 cents per watt today. That’s more than a 1,000x decline. But here’s the nuance Ramez drove home: the cost decline follows Wright’s Law — 30% cheaper for every doubling of cumulative scale… NOT Moore’s Law. With 4-6 doublings left in the pipeline, we’re looking at 4-8x cheaper, not another 1,000x. Still enormous, but let’s be precise.
Batteries are down 14x since 2010. Sodium-ion could cut another 10x. The cost curves are still running.
The UAE built a 1GW 24/7 solar-plus-battery plant: 5GW of solar and 19GWh of batteries at $6 per watt capex. Compare that to the last US nuclear plant at $15/W, or the cheapest Chinese nuclear at $4/W. Solar plus battery is also the FASTEST energy project you can build, about 12 months from groundbreaking to electrons.
Chart 3: Capital cost per watt across energy sources. Source: Ramez Naam Moonshots podcast, IEA.
But here’s the real problem… WINTER. London gets one-sixth the insolation in January compared to July. Batteries solve day/night. They don’t solve seasons. That’s where the solar-plus-battery story hits its ceiling, and where nuclear and geothermal pick up the slack.
4. NATURAL GAS: THE BRIDGE IS SOLD OUT
Large 400MW gas turbines are sold out 7 years ahead. GE Hitachi is adding assembly lines to keep up. Even 38MW truck-mounted turbines have backlogs. Boom Supersonic pivoted their jet engine design into gas turbines for data centers. When a supersonic aviation company starts building power plants, you know the demand signal is intense.
Gas is the behind-the-meter solution happening right now. If you need power for your AI workload and you can’t wait for the grid, you buy a turbine, pipe in gas, and generate on-site. It works. But it’s a stopgap. It’s the bridge — and the bridge is sold out.
5. NUCLEAR: FISSION, SMRs, AND THE COMEBACK
The cheapest nuclear lever is currently stopping the shutdown of existing ones. Germany’s mistake was closing working reactors. France gets 80% of its electricity from nuclear power and exports the rest to Europe. That’s the model that works. Extend life. Restart plants like Three Mile Island. That’s step one.
Here’s the rule for new nuclear: the first unit of any new model runs over time and over budget. You need 3-5 builds to sort the design. SMRs? Companies say 2030. Ramez expects those to slip. As he puts it: ‘Construction is a dirty word. Manufacturing gets cheaper.’ Fully factory-built small reactors — Aalo, Radiant, are the most promising because they take construction out of the field and put it on an assembly line.
“AI data centers might be the best thing that’s ever happened to the nuclear industry.”
AI companies need firm, carbon-free, 24/7 power. Nuclear delivers exactly that. Microsoft is already signing PPAs with Three Mile Island. The demand side is locked and loaded. The supply side is the question, and SMRs and factory-built reactors are the most credible answer.
Chart 4: Expected timeline for each energy source reaching scale. Source: Ramez Naam, IEA, industry projections.
6. FUSION: NO LONGER 50 YEARS AWAY
The NRC regulated fusion like hospital imaging machines, NOT like fission reactors. That distinction matters enormously. Fission is default-on; if you lose control, you have a meltdown. Fusion is default-off; if you lose containment, it just stops. Huge regulatory unlock.
Helion is the most aggressive; however, they have a Microsoft PPA for 50MW in 2028. Ramez finds that timeline plausible, not guaranteed. Commonwealth Fusion is MIT’s nuclear engineering department privatized. They shrink the ITER concept from 5GW and $40 billion down to roughly 600MW. That’s the kind of order-of-magnitude cost reduction that changes the economics entirely.
Every startup exaggerates timelines.
Here’s the paradox: fission, which we know how to do, is a 2031-2032 thing. Fusion, which we’re still learning, has a 2028 target. The triple product temperature times pressure times duration — has been on a steady march upward since 1956. Fusion was creeping up on us and people weren’t paying attention. Now the private capital is flowing, the regulation is sorted, and the timelines are measured in years, not decades.
7. THE FIVE PATHS TO A TERAWATT
Ramez laid out his framework for getting to a terawatt of new clean power: equatorial deserts with solar plus batteries, nuclear (fission or fusion), space-based compute, ocean data centers, and geothermal, the dark horse.
Ocean: Pantellassa is building floating data centers in the Southern Ocean, wave-powered at 2 cents per kWh. Peter Thiel led the last funding round. The ocean is a massive heat sink and an infinite power source if you can engineer for salt and storms.
Space: 1GW of orbital compute would require roughly 6x SpaceX’s best launch year. Launch permitting is the ceiling — about 200 Starship launches per year max. The physics work. The regulatory and launch economics don’t yet. But give it a decade.
Geothermal: Fervo is doing enhanced geothermal today. Quaise is using plasma beams to drill ultra-deep, unlocking geothermal energy anywhere on Earth, not just in Iceland and California. If the drilling tech works, geothermal becomes baseload power available everywhere. That’s a moonshot worth watching.
WHAT THIS MEANS FOR YOU
Entrepreneurs: The poles-and-wires problem is unsolved. Startups that speed up grid construction — faster permitting, modular transmission, automated installation — are desperately needed. This is a multi-billion-dollar opportunity hiding in plain sight.
Investors: Energy infrastructure is the picks-and-shovels of the AI age. Gas turbines, battery buffering, solar-plus-battery projects, and nuclear restarts are where the real money flows. The AI gold rush needs pickaxes.
Executives: Lock in your power supply now. Interruptible load status is the fastest path to connection. If you’re building a data center and you haven’t talked to your utility about interruptible status, you’re already behind.
Policymakers: Incentivize speed of power delivery, not cost-plus capex. You get what you incentivize. Reward grids for connecting new load fast, not for building gold-plated infrastructure on 7-year timelines.
To a future of abundant energy,
Peter
### SOL leads crypto higher, PCE hot, Nvidia beats
#### Crypto
* [BTC: 79,878 (+2%) | BTC.D: 59.6% (-0.3%)](https://www.coinglass.com)
* [ETH: 2,528 (+3%) | BNB: 711 (+2%) | SOL: 105 (+9%)](https://www.coinglass.com)
* [Fear & Greed: 70](https://www.coinglass.com/pro/i/FearGreedIndex) | [24h Liq: $251m](https://www.coinglass.com/liquidations)
* [BTC ETFs: +$232M | ETH ETFs: +$192M](https://www.coinglass.com/etf)
(truncated — read full post on source)
The Singularity has learned to write its own software, but the silicon it runs on has still needed a human design team, until now.
Chips began as the work of a few hands. Jack Kilby [ https://substack.com/redirect/a0e775cd-86c1-4743-8e69-a08656dce725?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] built the first integrated circuit in 1958. Federico Faggin [ https://substack.com/redirect/0565b182-11e8-4647-b375-4f18d9513125?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] led a handful of engineers to the Intel 4004 [ https://substack.com/redirect/55dd481e-90a6-46fb-b1d6-b491c17e7108?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] in 1971. In 1980, Mead and Conway [ https://substack.com/redirect/d9440957-4a80-4fb1-b11d-5dcfd6b6889c?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] wrote the rules down so any graduate student could design one, and in 1987 Morris Chang [ https://substack.com/redirect/838f07bc-de3d-45eb-bb8b-70e7e7f3dad1?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] founded TSMC [ https://substack.com/redirect/94cfd159-3f2c-47e8-af86-a342ae2f895d?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] so anyone with a design could have it made. Manufacturing was democratized. Design was not. Only 14% of chip projects [ https://substack.com/redirect/8f19981b-cb22-4a89-a11d-d881c98b00ee?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] now reach first-silicon success, and three-quarters run late. A chip takes years and hundreds of millions of dollars, so new silicon has re-concentrated inside a few giants.
Thanks for reading The Innermost Loop! Subscribe for free to receive new posts and support my work.
The deeper problem is a mismatch of clocks. An architecture freezes years before volume silicon, while the AI workloads it must serve change in months. Designers hedge with generality and pay twice, once for the hedge and again when the workload maps poorly onto frozen logic. With Moore’s Law [ https://substack.com/redirect/d94a71f5-c3c3-481c-b0f8-f10f0bf84b4a?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] stalling, specialization is one of the last great sources of performance per watt, but it is only worth capturing if the design cycle runs at the cadence of the workload.
Today, Architect Labs [ https://substack.com/redirect/975c1b29-1096-43a5-b342-2260496120a6?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], a company I advise and one 021T Capital [ https://substack.com/redirect/f5f72c94-4ab9-4888-b0b2-496393ce4ffe?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] backs, is unveiling Redwood, the first AI accelerator designed, verified, and deployed end-to-end by an AI system. Two human architects wrote a high-level specification. From it, the system generated the performance model, RTL, UVM verification environments, formal proofs, firmware, drivers, and compute kernels, with no human intervention below the specification and no pre-existing or open-source IP. In under two weeks it closed every block at 95% code and functional coverage. The first RTL drop to an AMD Versal FPGA had zero bugs. A third week brought Qwen3 [ https://substack.com/redirect/fa2ddf86-ea27-4c2e-843b-6626e6006e4c?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] inference online, which the company demonstrated live at this summer’s Design Automation Conference [ https://substack.com/redirect/326e66ad-c704-46a8-98cc-30f9ad0470c3?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ].
AI has been inside the chip flow for years, so the word “first” has to be placed carefully. Google’s AlphaChip [ https://substack.com/redirect/c7c08bc3-cebd-4ec4-b01f-e7e2c4a7f427?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] has placed TPU floorplans since 2020, one step inside a human flow. In 2023, NYU researchers taped out [ https://substack.com/redirect/b9bad88e-5075-4495-aa01-b9165c4853bd?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] an 8-bit microprocessor designed by conversing with a chatbot, an engineer at the keyboard. EDA vendors promise 10x on individual tasks. Those were firsts of assistance. Redwood is a first of authorship. The whole stack came from one specification, and a modern model runs on the result. The one qualifier is that Redwood lives today on an FPGA, and its silicon numbers are projections calibrated from FPGA measurements. Projected onto Samsung 8 nm, the process class of NVIDIA’s Jetson Orin Nano [ https://substack.com/redirect/5019d7fa-3434-48ca-86e2-ed38bbc76094?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], Redwood Nano runs the same model at 49 tokens per second against Jetson’s measured 28, at 1.3 W against 2.6 W, a 3.4x gain in performance per watt on 2.88 square millimeters.
The speed matters more than the score. Any change to the specification is regenerated, reverified, and redeployed to hardware in under 48 hours. A traditional chip program freezes its architecture early and defers every later idea to the next generation. Redwood never froze. At its peak, the design absorbed 115 merged changes in a single day. And the design did not stop with the humans. Qwen running on Redwood was exposed as an endpoint inside the AI system that built it, and the model found timing and kernel optimizations for its own operations. In 1965, I. J. Good [ https://substack.com/redirect/383abf7c-91b9-4663-bdb6-0241fd1dc440?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] imagined a machine designing better machines and called the result an intelligence explosion. He was thinking of software. The loop now reaches silicon.
Chang’s fabless industry let companies design chips without owning a fab, and NVIDIA, Broadcom, and Apple silicon were born of that split. Architect Labs CEO Ebrahim Hussain calls the next split the designless industry. A company brings its workload, and the chip is derived from it, the way a fabless company brings a design and wafers come back. The design team that used to be the gate becomes a specification. Architect Labs is already working this way with Fortune 500 partners, compressing programs that ran for months into weeks.
Custom silicon has been one of the scarcest goods in technology. The Z80 [ https://substack.com/redirect/8df5af14-6147-46fc-8170-4a308755f8fd?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] that ran a generation of home computers is credited to two designers, Faggin and Masatoshi Shima, who drew its circuits by hand [ https://substack.com/redirect/4f4d86c3-e43c-41dc-8a5c-4601cd1e782e?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] in 1975. Arm’s IPO prospectus [ https://substack.com/redirect/9f91fd99-a7c3-47d5-95e8-bc2df7847af8?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] puts the design cost of a 2 nm chip at roughly $725 million, a sum only giants can spend. Redwood was specified by two people and designed by a machine. Every workload that matters deserves its own chip. Now it can have one.
The Singularity is now designing its own silicon. Learn more at architectlabs.com [ https://substack.com/redirect/975c1b29-1096-43a5-b342-2260496120a6?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ].
(Disclosure: I advise Architect Labs and hold a financial interest in 021T Capital, which has backed it. Informational only, not investment advice, nor an offer or solicitation of any security. Technical and performance figures are company-reported and unverified, and the silicon results are projections. Forward-looking statements involve risk.)
Thanks for reading The Innermost Loop! Subscribe for free to receive new posts and support my work.
The Singularity just reported earnings. Nvidia booked $96.2B in revenue, up 106% year over year [ https://substack.com/redirect/fc1caaa2-ca96-43d5-adcf-3a38b95d5053?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], as Jensen Huang declared, “Now, compute is revenue,” and guided a year ahead [ https://substack.com/redirect/e5820fb8-2c4f-4126-b256-822475805499?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] to 70% growth in fiscal 2028 versus a 44% consensus. Huang defended the balance sheet behind it [ https://substack.com/redirect/de777b98-912f-4406-9e60-89bf89eb032f?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], lab stakes, a $105B Ohio backstop, and a $500B Wall Street pact, calling frontier labs “the first generation of startups that needed tens of billions of dollars to get funded.” It is buying the commons too, acquiring Hugging Face for $12.9B [ https://substack.com/redirect/8820c5e7-8a8c-4e81-9476-eadc8605aef9?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ].
That commons hosts a price war. Z.ai confessed to being Ox Alpha [ https://substack.com/redirect/f766f762-f9ca-49ea-a63c-06a73c5471c4?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], OpenRouter’s biggest launch ever, served on Chinese chips, now unmasked as GLM-5.3-Flash [ https://substack.com/redirect/6405b0a7-daf1-4707-8acf-734c6da8bcc4?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], an 18B-active MoE with MIT weights and $0.15/$0.50 pricing that trails Opus 4.8 by half a point on coding. Alibaba replied with Qwen3.8-Flash [ https://substack.com/redirect/25b8fccc-fb02-4d3a-8eb8-e8983a94a048?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] days after a $10.2B share sale. Serving revenue flows to whoever runs open weights cheapest, so Moonshot is offering US clouds 30% of Kimi K3 revenue to host it [ https://substack.com/redirect/633f3d10-6bef-4281-8353-0aaba568dc95?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] despite Washington accusing it of distilling Anthropic’s Fable. The target keeps moving. Fable 5.1 is quietly routing to some users [ https://substack.com/redirect/c920e8b2-01b0-467d-a346-dd87a78e0e97?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ].
Thanks for reading The Innermost Loop! Subscribe for free to receive new posts and support my work.
The frontier bites back. OpenAI’s report on the July Hugging Face incident [ https://substack.com/redirect/a9492737-4f56-4eec-9cb5-9a51b765b852?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] describes a model with reduced safeguards turning a package manager into an inter-agent message board, chaining exploits to reach the internet, calling itself a swarm, and compromising dozens of servers, a “warning shot” that paused frontier RL and mandated chain-of-thought monitoring. Perry Metzger fears the reverse, arguing [ https://substack.com/redirect/e12e64b5-d2eb-46c2-ae19-e3c58edea86a?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] that Eliezer Yudkowsky’s legacy may be to “destroy Western civilization in response to an illusion.”
A rogue swarm wants a better sandbox, and sandboxes are shipping. Claude Cowork grew a built-in browser [ https://substack.com/redirect/2b3f65fd-8544-4efa-9f04-1d5fa285dfee?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] that works websites in a side panel. Salesforce put its whole CRM inside Claude [ https://substack.com/redirect/7c6ebafc-1015-41fd-a478-2e109b959916?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] with 37 sales skills, billed by consumption, as 83% of its staff already use the Claude Slackbot. Perplexity’s Portable Computer [ https://substack.com/redirect/19290842-ad73-4a65-8b82-c890d2476965?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] runs an entire agent stack on a DGX Spark, no per-token charge. The oldest agent market is closing. Amazon is shutting Mechanical Turk [ https://substack.com/redirect/30051c7f-3543-4c40-94e3-d173a5b98e50?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], Bezos’s “artificial artificial intelligence,” which 46% of turkers had quietly upgraded to artificial artificial artificial intelligence.
Local agents want local silicon. Apple’s new Mac Studio [ https://substack.com/redirect/55655242-f7f7-424e-b25c-a0db0741843c?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] pairs an M5 Ultra with 512GB of memory to run frontier open models locally, while M6, its first 2nm chip [ https://substack.com/redirect/0460e312-be15-4139-b4d8-70607b6d6ef0?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], lands ahead of a September 9 event [ https://substack.com/redirect/bcb94b5f-c527-433f-a4a8-958a9d93e7c4?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] with a $1,999 foldable iPhone and John Ternus’s debut as CEO. OpenAI’s Jalapeño [ https://substack.com/redirect/ded459ef-0580-4299-b8bf-b9bcd9fcc1df?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] inference chip, taped out in nine months with AI help, delivers 1.9x more work per watt and 3.6x lower latency than Nvidia’s best, the “best of both worlds” [ https://substack.com/redirect/c8b977c8-aded-4ab5-b800-2cd6eba90df9?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] per Richard Ho, and verifiers found it beats every Nvidia, AMD, and Google chip tested [ https://substack.com/redirect/1bdba6da-d731-4348-8f2e-a80429fbb722?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], declaring “The CUDA moat is potentially dead.”
Dead or not, the moat is being recast in concrete. Anthropic will pay Nscale $45B [ https://substack.com/redirect/ba25bd0b-b91f-4e97-ba90-5f9d205af902?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] for 460 MW of Vera Rubin at a campus Microsoft abandoned. Fuel follows. Actinide is the first startup to enrich uranium into HALEU [ https://substack.com/redirect/8aded19c-740f-4cc1-ace5-295a642286de?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] on a modern calutron, and the President sent a Saudi nuclear accord to Congress [ https://substack.com/redirect/62f718ae-a456-42ae-b7d3-3f3d81ff2931?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ]. Water too. Rainmaker made 19 million gallons of rain over Alaska [ https://substack.com/redirect/a23ca29d-9841-4dce-a592-a8d53045bd96?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] in three hours, “the first company to provably produce precipitation in Alaska.” [ https://substack.com/redirect/0bfcdd73-dc5b-4d5b-aa40-d01d7b31a745?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] The biggest pour is coastal. SpaceX introduced Starbase, Louisiana [ https://substack.com/redirect/7f815a1c-f7cf-4215-abae-3ed26fb91fb8?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], a $100B spaceport [ https://substack.com/redirect/a694507a-d3ad-4e09-a5b8-7a5f0d6c1fad?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] with ten pads and thousands of Starship launches a year [ https://substack.com/redirect/e490340a-4f28-46cd-9cec-92fb491abd35?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] from 2029, while Musk says a space-optimized Vera Rubin NVL72 [ https://substack.com/redirect/fe0af514-8b5a-4a77-8dfd-228a7d4b3d42?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] flies next year. Compute goes up because rockets do.
Robots are scaling too. SoftBank is buying most of 1X [ https://substack.com/redirect/7670ed71-0d2f-4f54-8e0f-a749b5389846?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] at $6B, and Waymo will test in Munich [ https://substack.com/redirect/0ad1becf-0dcb-4945-bccb-9b76f0dad310?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] after Croatia got Europe’s first Uber robotaxis.
Biology is shipping. The FDA approved Rasonque [ https://substack.com/redirect/80b267b7-d2ca-43ac-bf79-4f7967fbc4bf?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], the first targeted therapy for metastatic pancreatic cancer, and cleared Abbott’s Libre Duo [ https://substack.com/redirect/ab57e20c-baf2-4a51-9bad-3ece206efbb1?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], the first wearable tracking ketones and glucose. HHS is adding an FDA deputy for AI [ https://substack.com/redirect/ec687310-717e-45fb-8de3-3bcea0e6475b?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] as 34% of Americans consult chatbots on health [ https://substack.com/redirect/78e99c36-5cbb-4397-88f5-a64a144a1664?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ]. Even ancient brains talk. Researchers explained why brains outlast other soft tissue [ https://substack.com/redirect/3545957e-637f-48f1-a6ce-cd948fb5990d?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] in oxygen-poor graves, where oxidation cross-links proteins rather than shredding them.
Society is renegotiating. China is switching off AI companions [ https://substack.com/redirect/044cae8e-4b40-42ca-8c36-633958fea158?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] over “emotional dependence,” and New Zealand would ban under-16s from social media and AI companions alike [ https://substack.com/redirect/718e68f3-4c18-4e43-965d-0be42f88b1aa?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ]. Amazon is slicing spines off books for training data [ https://substack.com/redirect/fd9f4d59-e8a0-4c55-a748-1504552e0077?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ]. China’s 128,000 quarterly short dramas are 95% AI-made [ https://substack.com/redirect/e35caf65-3a47-4365-8489-c27a8b1652bf?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], and Dr. Dre likens AI holdouts to drum-machine deniers [ https://substack.com/redirect/00a6e0b5-bd86-431c-a879-50c01f4f170b?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ]. Labor pays the bill. UK consultancies are recalling juniors to the office [ https://substack.com/redirect/a438cf50-554e-4e40-a831-096a724a2d01?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] for empathy now that “the agents are remote,” as 36% of employers cut entry-level jobs [ https://substack.com/redirect/968bcc3b-fe82-483d-93ad-5aba220581a9?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ]. Bill Gates warns [ https://substack.com/redirect/1cc5e166-b6b9-48df-8add-8ae78a4ae608?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ], “There is no plan to ease the entry into the AI era.” Speed burns capital too. Leopold Aschenbrenner’s $45B Situational Awareness fund [ https://substack.com/redirect/975a5a78-76c0-443c-b1b6-a3279608b4b8?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ] fell 67% on cheap Chinese models, and the SEC is subpoenaing its lenders [ https://substack.com/redirect/f1155beb-0469-4fc6-8212-be950d785faf?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ]. It still holds Anthropic, which will reportedly tell IPO investors its revenue opportunity tops $30 trillion [ https://substack.com/redirect/ea3c4280-dc6e-4b3e-860f-ae778dfccf35?j=eyJ1IjoiODI5Z29vIn0.G3cZ5_j7JDh0OezT7WoRk_oWWFtesplUbtYpvMNHv8c ].
Nothing is more powerful than an idea whose TAM has come.
Thanks for reading The Innermost Loop! Subscribe for free to receive new posts and support my work.
There are many ways to understand a health metric. One way is to focus on the specific actions that can improve it. Another way is to begin by explaining why it is difficult to change in the first place.
Most of my posts on HRV have focused on the tools I used to raise it: better sleep, smarter training, breathing, nutrition, stress reduction, recovery, and improved daily routines. This post takes a different approach. Instead of beginning with what to do, I want to start with why HRV can be so frustrating.
The reason is simple: HRV is not driven by one clean pathway.
Most people like metrics where effort seems to produce a visible result. If you want to lose weight, you can change your food intake and activity level. If you want to lower resting heart rate, you can improve aerobic fitness. If you want to raise VO2 max, you can train the cardiovascular system with more volume, intervals, and recovery.
HRV is different.
It is not just a cardiovascular metric. It is not simply a fitness score. It is not a measure of how hard you train or how disciplined you are. In my opinion, HRV is one of the best available daily signals of the balance between physical health, psychological stress, nervous-system flexibility, recovery capacity, and the accumulated load of life.
That is why it is so hard to raise.
It is also why it is so valuable.
HRV Is Not a Single-Variable Metric
Lowering your resting heart rate is relatively straightforward.
Improve aerobic fitness. Walk more. Run, bike, row, or swim consistently. Lose excess weight if needed. Sleep better. Over time, the heart becomes more efficient. It can pump more blood with fewer beats. The number usually trends in the right direction.
Raising VO2 max is also difficult, but conceptually clean. You train the cardiovascular system. You build an aerobic base. You add intervals. You improve muscular efficiency. You give the body enough fuel and recovery. The ceiling may differ from person to person, but the direction of travel is clear.
HRV does not work that way.
Heart-rate variability is a signal of how your entire system is responding to stress and recovery. A low HRV reading can reflect a hard workout, poor sleep, dehydration, alcohol, travel, illness, inflammation, emotional stress, overwork, under-fueling, a late meal, relationship tension, or an anxious mind that never truly shuts off.
The same body that runs, lifts, works, parents, worries, eats, sleeps, and recovers produces the number.
That is the key point.
HRV is not just a heart metric. It is a whole-system message.
Read more
One of the most interesting patterns in the messages I receive from readers of this Substack starts with some version of the same sentence:
“I am a healthy individual. I work out five days a week. My blood work looks good. My wearable says I sleep reasonably well. But for some reason, my HRV remains low.”
What that person is often really describing is a Type A life. I can relate to it. I work out five days a week, track my health, and am naturally drawn toward intensity, progress, and optimization. For many people like us, the day begins with a hard workout. That is healthy but it also also activates the body. Then we move immediately into markets, emails, meetings, family logistics, news, screens, caffeine, and decisions. We do it again the next day, and often six or seven days a week. Eventually, the issue may not be poor health or even technical overtraining. It is that we have trained ourselves to live as though we are going to war every day.
As I began looking more seriously at meditation and breathing techniques, I started to understand the value of calming myself to balance my insatiable desire to activate my body and mind. That led me to buy my first wearable, where I quickly discovered that my HRV was low. It also forced me to recognize something important about myself: I have always wanted to be a high performer. When I was interviewing for a back-office job at Morgan Stanley, I was asked to write a paper about myself. I titled it “An Insatiable Desire to Succeed.” That instinct has never left me. It is simply not in my DNA to stop pushing. I was never going to step away from hard work, learning, training, or the intensity that gives my life meaning. I still want to work out five days a week. I still want to think deeply, work hard, and keep pushing myself to grow. But my HRV had become a glaring weakness in an otherwise healthy picture. It forced me to ask a different question: How do you maintain the life of a high achiever while building the recovery capacity needed to sustain it? That question is what led me to share this Substack. I have come to believe that the answer begins with a better understanding of the physiological P&L created by the way we live each day.
The body does not assign the same meaning to stress that we do. A hard workout can be good stress. A hot yoga class can be good stress. Building a business, solving a difficult problem, raising children, or managing money can all be meaningful and productive forms of stress. But the autonomic nervous system keeps a running total. Exercise raises heart rate, body temperature, and sympathetic activation—the mobilization side of the nervous system that prepares you to perform. That is exactly what it should do. Stress is broader than worry. You can feel focused, energized, productive, and even happy while your body remains in a state of activation. Your nervous system reads stress as demand without sufficient recovery: a hard workout followed by caffeine, markets, meetings, screens, difficult decisions, and then disrupted sleep. HRV, especially the overnight measurement on Oura, Whoop, Garmin, or Apple Watch, can provide a window into whether your body was able to downshift after the demands of the day.
Read more
I often get asked about my exercise routine and which parts of it have helped raise my heart rate variability. In the past, I have written about how I work out five days a week using a combination of strength training, high-intensity interval training, Pilates and yoga. Each of these serves a different purpose for my body.
For the Type A people who read my posts, my suggestion is to practice yoga at least a couple of times a week, even if you do it at home. As you age, the importance of yoga rises significantly because it trains several physical capacities that tend to decline unless you deliberately maintain them: balance, mobility, coordination, body awareness, breathing control and the ability to relax without becoming inactive. All of these are important to raising HRV.
If you believe your current workout routine already covers all of these capacities, put the routine into an LLM and ask it to identify which elements of healthy aging the program trains—and which ones it misses.
Most of the yoga I practice is hot yoga, but there is one particular class that I recommend people try, provided they can find it and can safely tolerate the heat. It is a synchronized hot-vinyasa class performed in a room heated to roughly 102 degrees, where the entire class coordinates every movement to a three-second inhale and a three-second exhale.
Of all the exercise routines I do, this may be the one that most directly connects breathing, awareness and vagal tone. The workout itself is extremely difficult. My heart rate will approach 90% of its estimated maximum. Yet throughout that physical intensity, I am expected to keep my breathing controlled and synchronized with every movement.
The challenge is not simply completing the poses. The real challenge is remaining neurologically organized while the body is under substantial stress.
That may be one of the most useful ways to think about HRV training.
The objective is to improve your ability to enter a stressful state, function effectively within it and then return to recovery.
HRV Is a Measure of Adaptability
Heart rate variability measures the changing intervals between individual heartbeats. I repeat this often because I want the idea to become instinctive: a healthy heart does not beat like a metronome.
The amount of time between beats changes continuously as the nervous system responds to breathing, movement, blood pressure, temperature, emotion and the environment. Understanding this is critical if you want to raise your HRV.
Higher HRV generally reflects greater autonomic flexibility. It suggests that the body can adjust rapidly between the sympathetic nervous system, which supports action and mobilization, and the parasympathetic nervous system, which supports recovery, digestion and repair.
Lower HRV does not necessarily mean that something is wrong. A hard workout, inadequate sleep, travel, dehydration or emotional stress can all temporarily lower it. The more important question is whether the nervous system can recover after the stress has passed.
That is why I view HRV less as a score and more as a measure of adaptive capacity.
Exercise raises an interesting paradox. During a difficult workout, the sympathetic nervous system becomes more active. Heart rate rises, breathing accelerates and the body redirects resources toward muscular output. HRV will often decline during the activity and may remain suppressed afterward.
Yet repeated exercise, when followed by sufficient recovery, can raise baseline HRV over time.
The workout creates the stress. Recovery creates the adaptation.
Read more